AI-RAN時代のRAN自動化、SON、RIC、rApps、xApps、dApps 2026年-2040年:機会、課題、戦略、予測
RAN Automation, SON, RIC, rApps, xApps & dApps in the AI-RAN Era 2026 2040: Opportunities, Challenges, Strategies & Forecasts
RAN(無線アクセスネットワーク)の自動化――これは、携帯電話インフラの中で最もコストがかかり、技術的に複雑で、電力消費の大きい部分である――は、モバイル通信事業者の AN(自律ネットワーク)が、L4(高度... もっと見る
日本語のページは自動翻訳を利用し作成しています。
実際のレポートは英文でご納品いたします。

|

|
サマリー
RAN(無線アクセスネットワーク)の自動化――これは、携帯電話インフラの中で最もコストがかかり、技術的に複雑で、電力消費の大きい部分である――は、モバイル通信事業者の AN(自律ネットワーク)が、L4(高度自律)そして最終的にはL5(完全自律)運用へと向かう道のりにおいて極めて重要な側面である。AI(人工知能)およびML(機械学習)と相まって、 RANの自動化は、OpEx(運用費)対収益比率の低減、エネルギー消費の最小化、CO2(二酸化炭素)排出量の削減、回避可能なCapEx(設備投資)の先送り、パフォーマンスの最適化、ユーザー体験の向上、そして新サービスの実現を通じて、モバイルネットワークの経済性を大きく変革する可能性を秘めています。
楽天モバイル、チャイナモバイル、STC(サウジ・テレコム・カンパニー)、TDC NET、およびその他数社の通信事業者は、すでに実稼働中のRAN運用において、特定のユースケース向けに限定的なレベルながらL4レベルの自律化を実現しています。 このレベルの「意図駆動型」かつ「閉ループ型」のRAN自動化がもたらす、実証済みかつ定量化可能なメリットには、顧客体験を損なうことなく20%のエネルギー節約を実現することから、毎年行われるハッジ巡礼などの大規模イベントにおけるセル障害を最大60%削減することまで多岐にわたる。 地上公共モバイルネットワーク以外にも、RANの自動化は携帯電話業界の他の分野でも注目を集めており、NTN(非地上ネットワーク)のリソースオーケストレーションや地上・衛星間の相互接続から、エージェント型AIを活用したプライベート5Gネットワーク管理、洋上携帯電話ネットワーク展開における適応型電力制御、ドローン対策のためのISAC (統合センシング&通信)による対ドローン作戦、さらには戦術的5Gネットワークの電波規制に至るまで、幅広いアプリケーションを支えています。
RAN自動化市場の起源は、2010年代初頭にさかのぼります。当時、SON(自己組織化ネットワーク)技術―― 組み込み型のD-SON(分散型SON)およびC-SON(集中型SON)の実装という形で――自己構成、自己最適化、自己修復を通じてセルラーネットワークの複雑性を軽減するために導入されたことに端を発しています。 より高いレベルの自律性の追求に加え、レガシー SON ソリューションにおけるマルチベンダー間の相互運用性、スケーラビリティ、および遅延に関する制限により、RAN のプログラム可能性と自動化のレベルをさらに高める標準ベースのコンポーネントを備えた Open RAN オートメーションへの移行が加速しています。 これらには、Near-RT(リアルタイム)およびNon-RT RIC(RANインテリジェントコントローラ)、SMO(サービス管理およびオーケストレーション)フレームワーク、rApps(RANアプリケーション)、xApps(拡張アプリケーション)、dApps(分散アプリケーション)などが含まれます。
特に、SMOおよびNon-RT RICレイヤー上でホストされる、一元的に調整されたrAppは、ネットワーク全体にわたるマルチベンダーRAN自動化において好ましいアプローチとして台頭しています。これは、特に新しいRANの入れ替えや展開契約において、ハイブリッドおよびオープンRANアーキテクチャがますます一般的になっていることが背景にあります。 さらに、SMOプラットフォームは、可観測性、インテリジェンス、インテント管理、および閉ループ自動化を結びつける、ドメイン横断的なネットワーク自律性の共通基盤として位置づけられています。スウェーデンの無線通信大手エリクソンから、スペインのプライベート5Gオーケストレーション専門企業Neutroonに至るまで、複数のSMOプロバイダーが、エンドツーエンドの管理と自動化のためのコアネットワークインターフェースをすでに組み込んでいます。
ブラウンフィールド事業者(AT&T、Verizon、Telus、Vodafone、 DT(ドイツテレコム)、スイスコム、STC、NTTドコモ、中華電信、テルストラなど)の間で、SMO/非RT型RICの導入が加速し始めています。これは、RANベンダー提供、サードパーティ製、および自社開発のrAppを通じて、数千カ所に及ぶセルサイト全体でのネットワークワイドな自動化を実現するためです。 これは、グリーンフィールド事業者の楽天モバイルが、10社の異なるRU(無線ユニット)およびDU/CU (分散型および集中型ユニット)ベンダーから供給された35万のセルサイトにおいて、自社開発およびサードパーティ製のrAppを統合した全国規模のRIC展開に続くものです。
DU/CUベンダーの消極的な姿勢がxAppsやNear-RT RICの導入を妨げてきた一方で、最近提案されたE3(Edge‑Enhanced Exposure) インターフェースへの関心が高まっています。これは、dAppsがOpen RANベースバンドノードと直接連携し、xAppsの10ミリ秒という遅延制限を超えた閉ループ制御を実現するための標準化されたメカニズムを提供するもので、5Gおよび将来の6G展開における下位層のパフォーマンス最適化、位置情報、統合センシング、スペクトル共有、干渉キャンセルなどを含みます。 RANベンダーやアプリケーション開発者(ノキア、NVIDIA、Radisys、IS-Wireless、Cohere Technologies、DeepSig、ISCO International、Unikie、Booz Allen Hamilton、ODC(ORAN Development Company)など)は、すでにE3インターフェースのサポートを表明している。 一部のベンダーが追求しているdAppsに代わるアプローチとして、サブスクリプション型のライセンスモデルを通じて、既存のRANプラットフォーム向けのソフトウェアアップグレードとして、独自のAIを活用したリアルタイム最適化機能を提供することが挙げられる。 例えば、エリクソンは最近、サービスプロバイダー向けのソフトウェアサブスクリプションサービスを開始した。このサービスでは、AI/MLモデルをRANベースバンドおよび無線機に直接組み込み、スケジューリング、リンク適応、ビームフォーミング、多層協調といったユースケースにおいて、マイクロ秒レベルの推論を通じてパフォーマンスと効率を向上させるものである。
一般に「AI-for-RAN」と呼ばれる、RANの自動化および最適化に向けたAI、ML、およびそれらの派生技術のより深い統合は、より広範なAI-RANの動きの中で最も商業的に成熟した側面である。この動きには、AI-and-RAN ? 共有されたGPU加速インフラ上でのRANと外部AIワークロードの共同ホスティング;および「AI-on-RAN」――モバイル加入者向けのエッジAIサービスの実現――も含まれる。 当初から AI ネイティブシステムとして標準化が進められている最初の 6G ネットワークが 2030 年頃に開始されると、ハードウェアに依存しないソフトウェア主導のイノベーションの範囲が大幅に拡大し、業界は完全自律的なネットワーク運用にさらに近づくものと予想されます。 また、RANデジタルツインもますます重要な役割を果たすと予想されており、これにより通信事業者は、AI対応のエアインターフェース機能を検証し、高忠実度の仮想環境において最適化アルゴリズムを学習させた上で、実際の6Gネットワークに導入することが可能になります。
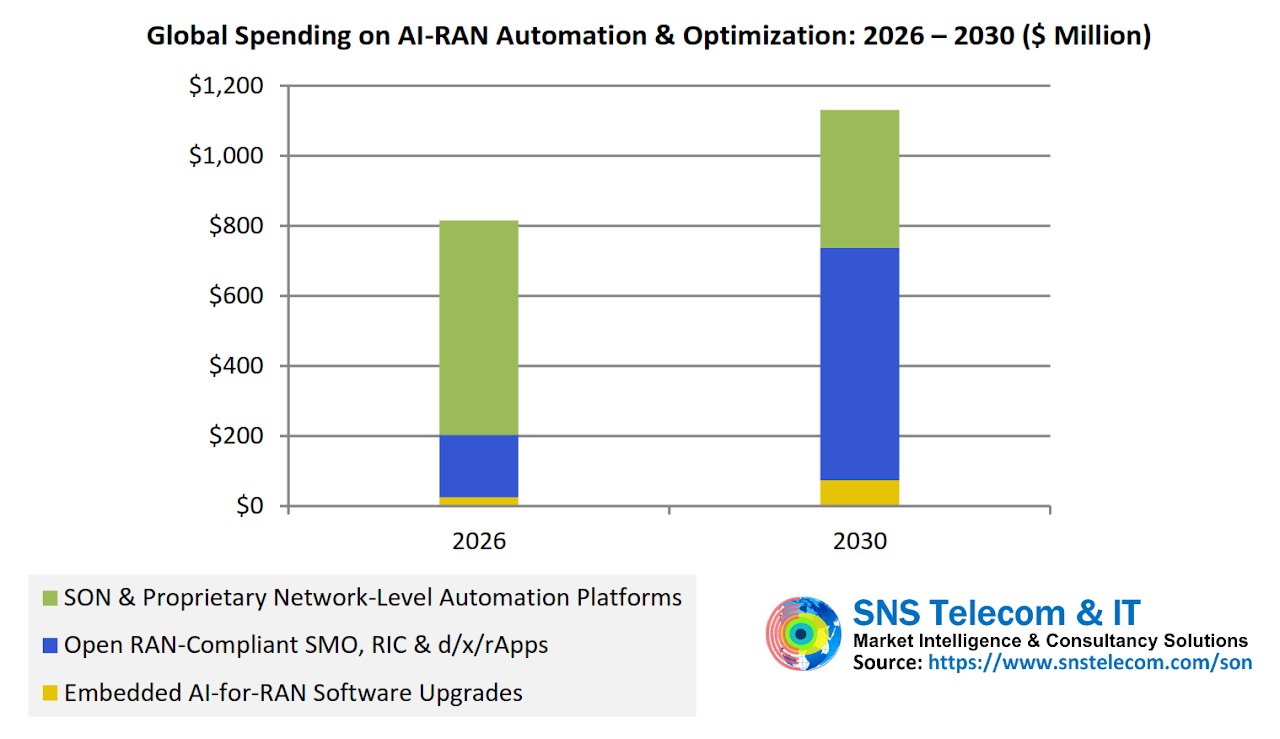
主に、ネットワークレベルでの一元的に調整されたSMO/RICを活用した自動化への投資拡大、および組み込み型リアルタイムインテリジェンスを実現するためのAI-for-RANソフトウェアのアップグレードや、RANノードにおける静的なルールベースのアルゴリズムの置き換えが牽引要因となり、 AI-RANの自動化および最適化ソフトウェア・サービスへの年間支出は、今後4年間で年平均成長率(CAGR)9%で拡大し、2030年末までに最終的に11億ドルに達すると予想される。より広範なRAN自動化市場( これには、従来のSONや独自仕様のネットワークレベル自動化、AI-for-RANによるアップグレード、Open RANのSMO/RICおよびd/x/rApps、RF計画ツール、自動テスト・測定ソリューションなどが含まれますが、同期間中に年平均成長率(CAGR)約4%で拡大すると予測されています。
当レポート「AI-RAN時代のRAN自動化、SON、RIC、rApps、xApps、dApps 2026年-2040年:機会、課題、戦略、予測」は、RAN自動化市場について詳細な分析を提供します。本レポートでは、バリューチェーン、市場の推進要因、導入の障壁、実現技術、機能領域、ユースケース、主要トレンド、将来のロードマップ、標準化、事例研究、エコシステム・プレイヤーのプロファイルおよび戦略などが網羅されています。また、2026年から2040年にかけてのRANおよびエンドツーエンドのモバイルネットワーク自動化に関する、世界および地域別の市場規模予測も提示しています。この予測は、3つのネットワークドメイン、9つの機能領域、3つのアクセス技術世代、12のユースケースカテゴリー、3つのネットワークタイプ、2つのサプライヤーカテゴリー、および5つの地域市場を対象としています。
本レポートには、レポート内で提示されているすべての数値予測に関する定量データを網羅した、関連するExcelデータシート一式が付属しています。
主な調査結果
このレポートには、次のような主な調査結果が示されている:
-
主にネットワークレベルでの一元的に調整されたSMO/RICを活用した自動化への投資拡大、および組み込み型リアルタイムインテリジェンスを実現するためのAI-for-RANソフトウェアのアップグレードや、RANノードにおける静的なルールベースのアルゴリズムの置き換えが主な要因となり、 AI-RANの自動化および最適化ソフトウェア・サービスへの年間支出は、今後4年間で年平均成長率(CAGR)9%で拡大し、2030年末までに最終的に11億ドルに達すると見込まれている。
-
広義のRAN自動化市場における総支出額は? これには、従来のSONや独自仕様のネットワークレベル自動化、AIを活用したRANアップグレード、Open RANのSMO/RICおよびd/x/rApps、RF計画ツール、自動テスト・計測ソリューションなどが含まれますが、同期間中に年平均成長率(CAGR)約4%で拡大すると見込まれている。
-
通信事業者は、L5ネットワークという長期的な目標の実現に向け、L4レベルのRAN(無線アクセスネットワーク)運用への着実な歩みを進めています。楽天モバイル、中国移動(China Mobile)、STC、TDC NETなどの事業者は、すでに商用ネットワーク上の特定のユースケースにおいて、限定的ながらL4レベルの自律運用を実現しています。インテント(意図)に基づいたクローズドループ型のRAN自動化がもたらす、実証済みかつ定量化可能なメリットは多岐にわたります。その例として、顧客体験を損なうことなく20%の省エネを実現することや、毎年行われるハッジ(大巡礼)のような大規模イベント時にセル停止(通信断)を最大60%削減することなどが挙げられます。
-
そのより高いレベルの自律性の追求に加え、従来のSONソリューションが抱えるマルチベンダー間の相互運用性、スケーラビリティ、および遅延に関する制約により、RANのプログラム可能性と自動化をさらに高める標準ベースのコンポーネントを用いたOpen RAN自動化への移行が加速している。
-
特に、SMOおよびNon-RT RICレイヤー上でホストされる、一元的に調整されたrAppは、ネットワーク全体にわたるマルチベンダーRAN自動化において好ましいアプローチとして台頭しています。これは、特に新しいRANの入れ替えや展開契約において、ハイブリッドおよびオープンRANアーキテクチャがますます一般的になっていることが背景にあります。 さらに、SMOプラットフォームは、可観測性、インテリジェンス、インテント管理、および閉ループ自動化を結びつける、ドメイン横断的なネットワーク自律性の共通基盤として位置づけられています。スウェーデンの無線通信大手エリクソンから、スペインのプライベート5Gオーケストレーション専門企業Neutroonに至るまで、複数のSMOプロバイダーが、エンドツーエンドの管理と自動化のためのコアネットワークインターフェースをすでに組み込んでいます。
-
ブラウンフィールド事業者(AT&T、Verizon、Telus、Vodafone、DT、Swisscom、STC、NTTドコモ、 中華電信、テルストラなど)の間で、SMO/非RT型RICの導入が加速し始めています。これは、RANベンダー提供、サードパーティ製、および自社開発のrAppを通じて、数千カ所に及ぶセルサイト全体でのネットワークワイドな自動化を実現するためです。 これは、グリーンフィールド事業者の楽天モバイルが、10社の異なるRUおよびDU/CUベンダーから供給された35万のセルからなるOpen RAN準拠のネットワーク全域において、自社開発およびサードパーティ製のrAppを統合し、RICを全国規模で展開したことに続く動きである。
-
DU/CUベンダーの消極的な姿勢がxAppsやNear-RT RICの導入を妨げてきた一方で、最近提案されたE3インターフェースへの関心が高まっている。このインターフェースは、dAppsがOpen RANベースバンドノードと直接連携し、xAppsの10ミリ秒という遅延制限を超える閉ループ制御を行うための標準化されたメカニズムを提供するものであり、 これには、5Gおよび将来の6G展開における下位層のパフォーマンス最適化、位置情報、統合センシング、スペクトル共有、干渉キャンセルなどが含まれます。 RANベンダーやアプリケーション開発者(ノキア、NVIDIA、Radisys、IS-Wireless、Cohere Technologies、DeepSig、ISCO International、Unikie、Booz Allen Hamilton、ODCなど)は、すでにE3インターフェースのサポートを表明している。
-
一部のベンダーがdAppに代わる選択肢として追求しているのは、サブスクリプション型のライセンスモデルを通じて、既存のRANプラットフォーム向けのソフトウェアアップグレードとして、AIを活用した独自のリアルタイム最適化機能を提供することです。 例えば、エリクソンは最近、サービスプロバイダー向けに、AI/MLモデルをRANのベースバンドおよび無線機に直接組み込んだソフトウェアサブスクリプションサービスを開始した。これにより、スケジューリング、リンク適応、ビームフォーミング、多層協調などのユースケースにおいて、マイクロ秒レベルの推論を通じて性能と効率を向上させている。
-
RANの自動化や最適化に向けたAI(人工知能)やML(機械学習)およびその派生技術の高度な統合(一般に「AI-for-RAN」と呼ばれます)は、より広範な「AI-RAN」の取り組みの中で、商用化の面で最も成熟した領域です。当初からAIネイティブなシステムとして標準化が進められている6Gネットワークが2030年頃に開始されれば、ハードウェアに依存しないソフトウェア主導のイノベーションの可能性が大幅に拡大し、業界は完全自律型のネットワーク運用へとさらに近づくものと期待されています。また、RANのデジタルツインもますます重要な役割を果たすと見込まれており、これにより事業者は、AIを活用した無線インターフェース機能を商用6Gネットワークに導入する前に、高精度な仮想環境で検証したり、最適化アルゴリズムを学習させたりすることが可能になります。
-
地上公共移動通信ネットワーク以外にも、他の分野におけるRANの自動化への関心が高まっています。これには、NTNにおける動的なリソースオーケストレーションのためのSMO/RICガバナンス層の活用や、地上RANインフラとの相互接続(モビリティやハンドオーバー管理から、オンデマンドでの衛星カバレッジの有効化に至るまで)が含まれます。特に、災害対応の場面において、その重要性が注目されています。
-
プライベート5G分野では、 RAN自動化アプリケーションが、ネットワークの展開と管理を簡素化するエージェント型AI、Wi-Fiとプライベート5Gネットワークの統合管理、既存事業者やその他のユーザーグループ間の動的周波数帯域割り当て、洋上セルラー展開における適応型電力制御、5G接続工場におけるフィジカルAIや産業オートメーションのための屋内測位など、多様なユースケースに向けて推進されています。 軍事作戦中の戦術的5Gインフラの電磁シグネチャを制限するための、ドローン検知および電波放射制御を目的としたISACなどが挙げられます。
-
最近の事例として、ノルウェーの海運会社カラー・ラインが運航する船舶において、NVIDIAの技術を搭載したエージェント型AIソリューションを導入し、プライベート5Gネットワークの自律的な最適化を実現したことが挙げられる。 日本では、国内のシステムインテグレーターであるNTT東日本が、プライベート5Gネットワークにおける送信電力の最適化や干渉低減をサポートする、AIを活用した自律型ネットワーク制御アプリケーション向けのRIC機能を評価するため、26社のベンダーと一連の試験を最近完了した。
-
そのノキアがHPE(ヒューレット・パッカード・エンタープライズ)からジュニパー・ネットワークスのSMO/RIC資産を買収し、VMwareが市場から完全に撤退したことで、Open RANの自動化エコシステムには統合の兆しが見え始めています。 今後、過去10年間のSONブームを彷彿とさせるようなM&A活動がさらに活発化すると予想される。しかし、アプリケーション分野においては、RANベンダー、サードパーティ開発者、さらにはモバイル通信事業者自身を含め、数十社もの企業がrApps、xApps、そして最近ではdAppsの開発に積極的に取り組んでおり、多様性に欠けることはない。
-
北欧の通信インフラ大手であるエリクソンとノキアは、互いのSMO/rAppエコシステムに参画することで、異例の連携を見せている。これは、SON時代の「ウォールド・ガーデン」型のアプローチから脱却し、真のベンダー横断的な自動化への道を切り開こうとしているものとみられる。
取り上げるトピック
その本報告書では、以下のトピックを取り上げています:
-
RAN自動化の概要
-
バリューチェーンとエコシステムの構造
-
市場の推進要因と課題
-
RAN自動化の機能分野
-
D-SON、C-SON、H-SON、Near-RT/Non-RT RIC、SMO、d/x/rApps、RAN向けAIソフトウェアのアップグレード、RAN計画ツール、およびテスト・計測ソリューションを含む、RAN自動化技術およびアーキテクチャ
-
ANR、PCI、RACHの最適化から、自動化されたセルシェーピング、高度なトラフィックステアリング、QoEに基づくリソース割り当て、省エネ、異常検知、動的なRANセキュリティ、適応型ネットワークスライシング、ISAC、NTNオーケストレーション、プライベート5Gの自動化、RANデジタルツインに至るまで、85件以上のRAN自動化ユースケースを検証
-
インテリジェントRANの実装における主要なトレンド。これには、SONからSMO/RICへの移行、閉ループ自動化、意図駆動型管理、組み込み型リアルタイムインテリジェンス、運用向けAI/ML、深層強化学習、ジェネレーティブAI、エージェント型AI、データ分析、およびアプリケーション認識などが含まれる。
-
セルラーインフラのRAN、コア、xHaulトランスポート各セグメントにわたる、ドメイン横断的なモバイルネットワーク自動化を実現する要素と適用シナリオ
-
複数の通信事業者グループ、国内の携帯電話事業者、およびプライベートネットワーク事業者における、25件の商用レベルのRAN自動化導入事例に関する詳細なケーススタディ
-
100社以上の通信事業者を対象とした、進行中のRAN自動化プロジェクトに関する世界的な調査。従来のSON、Open RAN、およびAI/MLを活用した自動化アプローチを網羅
-
RAN自動化の今後のロードマップ
-
標準化と共同取り組み
-
RANベンダー、コアおよびxHaul分野で事業を展開する企業、RIC、SMO、OSSプラットフォームプロバイダー、d/x/rApp開発者、AI/ML技術の専門家、RAN計画ソフトウェアサプライヤー、テスト・計測ソリューションプロバイダーなど、300社を超えるエコシステム参加企業の概要と戦略
-
RAN自動化ソリューションプロバイダーおよびモバイル通信事業者に向けた戦略的提言
-
2026年から2040年までの市場分析と予測
予測のセグメンテーション
以下の各サブマーケットおよびそのサブカテゴリーについて、市場予測が提供されています:
-
RAN自動化の機能領域
-
従来のSONおよびベンダー固有のRAN自動化
-
SONおよび独自(プロプライエタリ)のネットワークレベル自動化プラットフォーム
-
リアルタイムRANインテリジェンス・自動化のためのAI活用型RANソフトウェア・アップグレード
-
SMO/RICおよびOpen RAN自動化
-
Non-RT RICおよびSMO
-
Near-RT RIC
-
rApps
-
xApps
-
dApps
-
RF(無線周波数)の計画・最適化ツール
-
試験・測定ソリューション
-
アクセス技術・世代別のサブ市場
-
ユースケースのセグメント
-
PCI、RACH および構成の自動化
-
モビリティ、ハンドオーバー、および負荷管理
-
RANリソースおよびパフォーマンスの最適化
-
エネルギー効率と持続可能性
-
周波数管理およびマルチRAT接続
-
ネットワークの癒しと保護
-
大規模MIMO、ビームフォーミング、および下位層の最適化
-
ネットワークスライシングと垂直型アプリケーション
-
ISAC、測位・追跡
-
ネットワーク計画と進化
-
自動化およびAIの活用
-
マルチドメインのユースケース
-
ネットワークの種類
-
パブリック・モバイル・オペレーターのネットワーク
-
NTNインフラストラクチャー
-
プライベート・セルラー・ネットワーク
-
サプライヤーのカテゴリー
-
RANベンダー
-
NTNインフラストラクチャー
-
サードパーティのサプライヤー
-
地域別市場
-
北米
-
アジア太平洋地域
-
ヨーロッパ
-
中東・アフリカ
-
ラテンアメリカおよび中米
発売日:2026年10月
ページ数:648
図表数:67
ページTOPに戻る
Summary
Automation of the RAN (Radio Access Network) – the most expensive, technically complex and power-intensive part of cellular infrastructure – is a key aspect of mobile operators' AN (Autonomous Network) journeys towards L4 (Highly Autonomous) and eventually L5 (Fully Autonomous) operations. In conjunction with AI (Artificial Intelligence) and ML (Machine Learning), RAN automation has the potential to significantly transform mobile network economics by reducing the OpEx (Operating Expenditure)-to-revenue ratio, minimizing energy consumption, lowering CO2 (Carbon Dioxide) emissions, deferring avoidable CapEx (Capital Expenditure), optimizing performance, improving user experience and enabling new services.
Rakuten Mobile, China Mobile, STC (Saudi Telecom Company), TDC NET and several other operators have already achieved a limited level of L4 autonomy for specific use cases in their live RAN operations. The proven, quantifiable benefits of this level of intent-driven, closed-loop RAN automation range from 20% energy savings without compromising customer experience to a reduction of up to 60% in cell outages during major events such as the annual Hajj pilgrimage. Beyond terrestrial public mobile networks, RAN automation is also gaining traction in other segments of the cellular industry, supporting applications ranging from NTN (Non-Terrestrial Network) resource orchestration and terrestrial-satellite interworking to agentic AI-enabled private 5G network management, adaptive power control in offshore cellular deployments, ISAC (Integrated Sensing & Communications) for counter-drone operations and emission control for tactical 5G networks.
The RAN automation market traces its origins to the early 2010s when SON (Self-Organizing Network) technology – in the form of both embedded D-SON (Distributed SON) and C-SON (Centralized SON) implementations – was introduced to reduce cellular network complexity through self-configuration, self-optimization and self-healing. The pursuit of higher levels of autonomy, coupled with the multi-vendor interoperability, scalability and latency-related limitations of legacy SON solutions, is accelerating the transition to Open RAN automation with standards-based components that enable greater levels of RAN programmability and automation. These include the Near-RT (Real-Time) and Non-RT RICs (RAN Intelligent Controllers), SMO (Service Management & Orchestration) framework, rApps (RAN Applications), xApps (Extended Applications) and dApps (Distributed Applications).
In particular, centrally coordinated rApps hosted on the SMO and Non-RT RIC layer have emerged as the preferred approach to multi-vendor RAN automation on a network-wide basis, especially as hybrid and Open RAN architectures become increasingly common in new RAN swap and rollout contracts. Additionally, SMO platforms are being positioned as a common foundation for cross-domain network autonomy that links observability, intelligence, intent management and closed-loop automation. From Swedish wireless giant Ericsson to Spanish private 5G orchestration specialist Neutroon, multiple SMO providers have already incorporated core network interfaces for end-to-end management and automation.
SMO/Non-RT RIC adoption is beginning to accelerate among brownfield operators – including but not limited to AT&T, Verizon, Telus, Vodafone, DT (Deutsche Telekom), Swisscom, STC, NTT DoCoMo, Chunghwa Telecom and Telstra – to enable network-wide automation across thousands of cell sites through RAN vendor-supplied, third-party and internally developed rApps. This follows greenfield operator Rakuten Mobile’s nationwide RIC deployment, along with in-house and third-party rApp integration, across its Open RAN-compliant footprint of 350,000 cells supplied by 10 distinct RU (Radio Unit) and DU/CU (Distributed & Centralized Unit) vendors.
While reluctance among DU/CU vendors has held back adoption of xApps and the Near-RT RIC, there is growing interest in the recently proposed E3 (Edge‑Enhanced Exposure) interface, which provides a standardized mechanism for dApps to directly interface with Open RAN baseband nodes for closed-loop control beyond the 10-millisecond latency limits of xApps, including lower-layer performance optimization, geolocation, integrated sensing, spectrum sharing and interference cancellation in 5G and future 6G deployments. RAN vendors and application developers – such as Nokia, NVIDIA, Radisys, IS-Wireless, Cohere Technologies, DeepSig, ISCO International, Unikie, Booz Allen Hamilton and ODC (ORAN Development Company) – have already committed to support the E3 interface. An alternative to dApps being pursued by some vendors is to offer proprietary AI-enabled, real-time optimization capabilities as software upgrades to existing RAN platforms through subscription-based licensing models. For example, Ericsson has recently launched a software subscription offering for service providers that embeds AI/ML models directly into RAN basebands and radios to improve performance and efficiency through microsecond-level inference for use cases such as scheduling, link adaptation, beamforming and multi-layer coordination.
Commonly referred to as AI-for-RAN, the deeper integration of AI, ML and their derivatives for RAN automation and optimization is the most commercially mature facet of the broader AI-RAN movement, which also encompasses AI-and-RAN – the co-hosting of RAN and external AI workloads on shared, GPU-accelerated infrastructure; and AI-on-RAN – the enablement of edge AI services for mobile subscribers. The launch of the first 6G networks – which are being standardized as AI-native systems from the outset – around 2030 is expected to significantly increase the scope for hardware-agnostic, software-led innovation and take the industry closer to fully autonomous network operations. RAN digital twins are also expected to play an increasingly important role, allowing operators to validate AI-enabled air interface features and train optimization algorithms in high-fidelity virtual environments before introducing them into live 6G networks.
Largely driven by growing investments in both centrally coordinated SMO/RIC-enabled automation at the network level and AI-for-RAN software upgrades for embedded real-time intelligence and the replacement of static rule-based algorithms in RAN nodes, annual spending on AI-RAN automation and optimization software and services is expected to grow at a CAGR of 9% over the next four years, eventually reaching $1.1 billion by the end of 2030. Total spending on the wider RAN automation market – which includes traditional SON/proprietary network-level automation, AI-for-RAN upgrades, Open RAN SMO/RIC and d/x/rApps, RF planning tools and automated test/measurement solutions – is expected to grow at a CAGR of approximately 4% during the same period.
The “RAN Automation, SON, RIC, SMO, rApps, xApps & dApps in the AI-RAN Era: 2026 – 2040 – Opportunities, Challenges, Strategies & Forecasts” report presents an in-depth assessment of the RAN automation market, including the value chain, market drivers, barriers to uptake, enabling technologies, functional areas, use cases, key trends, future roadmap, standardization, case studies, ecosystem player profiles and strategies. The report also provides global and regional market size forecasts for RAN and end-to-end mobile network automation from 2026 to 2040. The forecasts cover three network domains, nine functional areas, three access technology generations, 12 use case categories, three network types, two supplier categories and five regional markets.
The report comes with an associated Excel datasheet suite covering quantitative data from all numeric forecasts presented in the report.
Key Findings
The report has the following key findings:
-
Largely driven by growing investments in both centrally coordinated SMO/RIC-enabled automation at the network level and AI-for-RAN software upgrades for embedded real-time intelligence and the replacement of static rule-based algorithms in RAN nodes, annual spending on AI-RAN automation and optimization software and services is expected to grow at a CAGR of 9% over the next four years, eventually reaching $1.1 billion by the end of 2030.
-
Total spending on the wider RAN automation market – which includes traditional SON/proprietary network-level automation, AI-for-RAN upgrades, Open RAN SMO/RIC and d/x/rApps, RF planning tools and automated test/measurement solutions – is expected to grow at a CAGR of approximately 4% during the same period.
-
Mobile operators are making tangible progress towards L4 RAN operations as they work towards the longer-term goal of L5 networks. Rakuten Mobile, China Mobile, STC, TDC NET and several other operators have already achieved a limited level of L4 autonomy for specific use cases in their live networks. The proven, quantifiable benefits of this level of intent-driven, closed-loop RAN automation range from 20% energy savings without compromising customer experience to a reduction of up to 60% in cell outages during major events such as the annual Hajj pilgrimage.
-
The pursuit of higher levels of autonomy, coupled with the multi-vendor interoperability, scalability and latency-related limitations of legacy SON solutions, is accelerating the transition to Open RAN automation with standards-based components that enable greater levels of RAN programmability and automation.
-
In particular, centrally coordinated rApps hosted on the SMO and Non-RT RIC layer have emerged as the preferred approach to multi-vendor RAN automation on a network-wide basis, especially as hybrid and Open RAN architectures become increasingly common in new RAN swap and rollout contracts. Additionally, SMO platforms are being positioned as a common foundation for cross-domain network autonomy that links observability, intelligence, intent management and closed-loop automation. From Swedish wireless giant Ericsson to Spanish private 5G orchestration specialist Neutroon, multiple SMO providers have already incorporated core network interfaces for end-to-end management and automation.
-
SMO/Non-RT RIC adoption is beginning to accelerate among brownfield operators – including but not limited to AT&T, Verizon, Telus, Vodafone, DT, Swisscom, STC, NTT DoCoMo, Chunghwa Telecom and Telstra – to enable network-wide automation across thousands of cell sites through RAN vendor-supplied, third-party and internally developed rApps. This follows greenfield operator Rakuten Mobile’s nationwide RIC deployment, along with in-house and third-party rApp integration, across its Open RAN-compliant footprint of 350,000 cells supplied by 10 distinct RU and DU/CU vendors.
-
While reluctance among DU/CU vendors has held back adoption of xApps and the Near-RT RIC, there is growing interest in the recently proposed E3 interface, which provides a standardized mechanism for dApps to directly interface with Open RAN baseband nodes for closed-loop control beyond the 10-millisecond latency limits of xApps, including lower-layer performance optimization, geolocation, integrated sensing, spectrum sharing and interference cancellation in 5G and future 6G deployments. RAN vendors and application developers – such as Nokia, NVIDIA, Radisys, IS-Wireless, Cohere Technologies, DeepSig, ISCO International, Unikie, Booz Allen Hamilton and ODC – have already committed to support the E3 interface.
-
An alternative to dApps being pursued by some vendors is to offer proprietary AI-enabled, real-time optimization capabilities as software upgrades to existing RAN platforms through subscription-based licensing models. For example, Ericsson has recently launched a software subscription offering for service providers that embeds AI/ML models directly into RAN basebands and radios to improve performance and efficiency through microsecond-level inference for use cases such as scheduling, link adaptation, beamforming and multi-layer coordination.
-
The deeper integration of AI, ML and their derivatives for RAN automation and optimization – commonly referred to as AI-for-RAN – is the most commercially mature facet of the broader AI-RAN movement. The launch of the first 6G networks – which are being standardized as AI-native systems from the outset – around 2030 is expected to significantly increase the scope for hardware-agnostic, software-led innovation and take the industry closer to fully autonomous network operations. RAN digital twins are also expected to play an increasingly important role, allowing operators to validate AI-enabled air interface features and train optimization algorithms in high-fidelity virtual environments before introducing them into live 6G networks.
-
Beyond terrestrial public mobile networks, there is growing interest in RAN automation for other segments, including the use of an SMO/RIC governance layer for dynamic resource orchestration in NTNs and interworking with terrestrial RAN infrastructure, from mobility and handover management to on-demand satellite coverage activation – particularly during disaster response scenarios.
-
In the private 5G segment, RAN automation applications are being pursued for diverse use cases, including agentic AI to simplify network deployment and administration, converged management of Wi-Fi and private 5G networks, dynamic spectrum allocation between incumbents and other user groups, adaptive power control in offshore cellular deployments, indoor positioning for physical AI and industrial automation in 5G-connected factories, ISAC for drone detection and emission control to limit the electromagnetic signature of tactical 5G infrastructure during military operations.
-
One recent example is the implementation of an NVIDIA-powered agentic AI solution for autonomous private 5G network optimization aboard vessels operated by Norwegian shipping company Color Line. In Japan, domestic integrator NTT East has recently concluded a series of tests with 26 vendors to evaluate RIC functionality for AI-enabled autonomous network control applications supporting transmit power optimization and interference mitigation in private 5G networks.
-
The Open RAN automation ecosystem is exhibiting signs of consolidation with Nokia’s acquisition of Juniper Networks' SMO/RIC assets from HPE (Hewlett Packard Enterprise) and VMware's exit from the market altogether. We anticipate seeing further M&A activity reminiscent of the SON boom in the previous decade. However, there’s no lack of diversity in the application segment with dozens of companies – including RAN vendors, third-party developers and mobile operators themselves – actively engaged in the development of rApps, xApps and, more recently, dApps.
-
Nordic telecommunications infrastructure giants Ericsson and Nokia are presenting an unusually united front by joining each other’s SMO/rApp ecosystems, seemingly moving away from the SON era walled garden approach to clear the path for true cross-vendor automation.
Topics Covered
The report covers the following topics:
-
Introduction to RAN automation
-
Value chain and ecosystem structure
-
Market drivers and challenges
-
Functional areas of RAN automation
-
RAN automation technology and architecture, including D-SON, C-SON, H-SON, Near-RT/Non-RT RICs, SMO, d/x/rApps, AI-for-RAN software upgrades, RAN planning tools and test/measurement solutions
-
Review of over 85 RAN automation use cases, ranging from ANR, PCI and RACH optimization to automated cell shaping, advanced traffic steering, QoE-based resource allocation, energy savings, anomaly detection, dynamic RAN security, adaptive network slicing, ISAC, NTN orchestration, private 5G automation and RAN digital twins
-
Key trends in intelligent RAN implementations, including the SON-to-SMO/RIC transition, closed-loop automation, intent-driven management, embedded real-time intelligence, operational AI/ML, deep reinforcement learning, Gen AI, agentic AI, data analytics and application awareness
-
Cross-domain mobile network automation enablers and application scenarios across the RAN, core and xHaul transport segments of cellular infrastructure
-
Detailed case studies of 25 production-grade RAN automation deployments across multiple operator groups, national mobile operators and private network operators
-
Worldwide review of ongoing RAN automation projects across over 100 operators, covering traditional SON, Open RAN and AI/ML-driven automation approaches
-
Future roadmap of RAN automation
-
Standardization and collaborative initiatives
-
Profiles and strategies of more than 300 ecosystem players, including RAN vendors, companies active in the core and xHaul segments, RIC, SMO and OSS platform providers, d/x/rApp developers, AI/ML technology specialists, RAN planning software suppliers and test/measurement solution providers
-
Strategic recommendations for RAN automation solution providers and mobile operators
-
Market analysis and forecasts from 2026 to 2040
Forecast Segmentation
Market forecasts are provided for each of the following submarkets and their subcategories:
-
Mobile Network Automation Submarkets
-
-
RAN
-
Mobile Core
-
xHaul Transport
-
RAN Automation Functional Areas
-
Traditional SON & Vendor-Specific RAN Automation
-
SON & Proprietary Network-Level Automation Platforms
-
AI-for-RAN Software Upgrades for Real-Time RAN Intelligence & Automation
-
SMO/RIC & Open RAN Automation
-
Non-RT RIC & SMO
-
Near-RT RIC
-
rApps
-
xApps
-
dApps
-
RF Planning & Optimization Tools
-
Test & Measurement Solutions
-
Access Technology Generation Submarkets
-
Use Case Segments
-
PCI, RACH & Configuration Automation
-
Mobility, Handover & Load Management
-
RAN Resource & Performance Optimization
-
Energy Efficiency & Sustainability
-
Spectrum Management & Multi-RAT Connectivity
-
Network Healing & Protection
-
Massive MIMO, Beamforming & Lower-Layer Optimization
-
Network Slicing & Vertical Applications
-
ISAC, Positioning & Tracking
-
Network Planning & Evolution
-
Automation & AI Enablement
-
Multi-Domain Use Cases
-
Network Types
-
-
Public Mobile Operator Networks
-
NTN Infrastructure
-
Private Cellular Networks
-
Supplier Categories
-
RAN Vendors
-
NTN Infrastructure
-
Third-Party Suppliers
-
Regional Markets
-
North America
-
Asia Pacific
-
Europe
-
Middle East & Africa
-
Latin & Central America
Release Date: October 2026
Number of Pages: 648
Number of Tables and Figures: 67
ページTOPに戻る
本レポートと同じKEY WORD()の最新刊レポート
- 本レポートと同じKEY WORDの最新刊レポートはありません。
よくあるご質問
SNS Telecom & IT社はどのような調査会社ですか?
SNSテレコム&IT (SNS Telecom & IT)はドバイに拠点をおき、通信技術やモバイル機器に関する継続的な非常に詳細なデータを提供しています。無線ネットワークインフラやビッグデータ、M2M... もっと見る
調査レポートの納品までの日数はどの程度ですか?
在庫のあるものは速納となりますが、平均的には 3-4日と見て下さい。
但し、一部の調査レポートでは、発注を受けた段階で内容更新をして納品をする場合もあります。
発注をする前のお問合せをお願いします。
注文の手続きはどのようになっていますか?
1)お客様からの御問い合わせをいただきます。
2)見積書やサンプルの提示をいたします。
3)お客様指定、もしくは弊社の発注書をメール添付にて発送してください。
4)データリソース社からレポート発行元の調査会社へ納品手配します。
5) 調査会社からお客様へ納品されます。最近は、pdfにてのメール納品が大半です。
お支払方法の方法はどのようになっていますか?
納品と同時にデータリソース社よりお客様へ請求書(必要に応じて納品書も)を発送いたします。
お客様よりデータリソース社へ(通常は円払い)の御振り込みをお願いします。
請求書は、納品日の日付で発行しますので、翌月最終営業日までの当社指定口座への振込みをお願いします。振込み手数料は御社負担にてお願いします。
お客様の御支払い条件が60日以上の場合は御相談ください。
尚、初めてのお取引先や個人の場合、前払いをお願いすることもあります。ご了承のほど、お願いします。
データリソース社はどのような会社ですか?
当社は、世界各国の主要調査会社・レポート出版社と提携し、世界各国の市場調査レポートや技術動向レポートなどを日本国内の企業・公官庁及び教育研究機関に提供しております。
世界各国の「市場・技術・法規制などの」実情を調査・収集される時には、データリソース社にご相談ください。
お客様の御要望にあったデータや情報を抽出する為のレポート紹介や調査のアドバイスも致します。
|
|