プライベート5G市場:2026年~2030年の機会、課題、戦略、および予測Private 5G Market: 2026 2030 Opportunities, Challenges, Strategies & Forecasts 2Gおよび3Gの時代において、プライベートセルラーネットワークは概してニッチなソリューションにとどまっていましたが、鉄道通信用のGSM-Rネットワークは、5GベースのFRMCS(Future Railway Mobile Communicat... もっと見る

サマリー2Gおよび3Gの時代において、プライベートセルラーネットワークは概してニッチなソリューションにとどまっていましたが、鉄道通信用のGSM-Rネットワークは、5GベースのFRMCS(Future Railway Mobile Communication System)への移行が計画されているにもかかわらず、現在も稼働を続けています。 2010年代初頭には、リオ・ティント社の西オーストラリア州鉱山事業向けプライベートLTEネットワーク、タンプネット社のオフショア4Gインフラ、iNET社のパーミアン盆地における700 MHzネットワークなど、プライベートLTEネットワークの導入が相次ぎ、 これらは、その後、広範な無線インフラ分野において、確立されたニッチなセグメントへと成長した動きの始まりとなった。しかし、3GPPが定義した5G仕様に基づくプライベート5Gネットワーク、すなわちNPN(非公開ネットワーク)が、多くの業界においてLTEに取って代わりつつあり、その市場ポテンシャルは従来の技術世代をはるかに上回っている。 ADNOC、エアバス、アルセロール・ミッタル、BASF、バイエル、ベルデン、BHP、BMW、 ボリデン、BP、カーギル、セラニーズ、シェブロン、CIMPOR、COSCO Shipping、CPF(チャロエン・ポックパン・フーズ)、デンカ、ドット・フーズ、DPワールド、デュラセル、エクイノール、EMSTEEL、 エティハド、フレックス、フォード、フォックスコン、ゲルダウ、グーグル、ハンコック・プロスペクティング、日立レール、ホームデポ、ハッチソン・ポート、ヒュンダイ、インテル、インベンテック、ジャガー・ランドローバー、ジョン・ディア、LGエレクトロニクス、LSエレクトリック、ルフトハンザ、リヨネル・バセル、マイヤー、 モーヴェ(セプサ)、ネスレ、ニューモント、ニューコア、OKI電気、アウトオクンプ、ペガトロン、ペトロナス、ポスコ、レプソル、リコー、 ロバート・ボッシュ、ザルツギッター、SNAM、スバル、武田薬品工業、テスラ、トヨタ、トリニティ・インダストリーズ、ウジミナス、フォルクスワーゲン、ウォルマート、WEG、ワールプール、ゼロックス、シャオミ・オート、ZF。
LTE技術と比較して、プライベート5Gネットワーク(地域によって5G MPN(Mobile Private Networks)、5Gキャンパスネットワーク、P5G、ローカル5G、あるいはe-Um 5Gシステムなどとも呼ばれる)は、 スループット、遅延、信頼性、可用性、接続密度といった点において、はるかに厳しい性能要件に対応できます。特に、5GのURLLC(Ultra-Reliable, 低遅延通信)およびmMTC(大規模マシン型通信)機能に加え、2030年代に向けた6Gネットワークへの将来を見据えた移行経路を備えていることから、機械、ロボット、制御システム間の産業用通信において、有線接続に代わる現実的な選択肢としての地位を確立しています。 さらに、総所有コスト(TCO)が比較的高いにもかかわらず、5Gの1つの無線ノードあたりの広範囲なカバレッジ、スケーラビリティ、決定性、セキュリティ機能、およびモビリティへの対応は、今後数年間で接続されるセンサーやその他のエンドポイントの数が大幅に増加すると予想されるIIoT(産業用IoT)環境において、干渉を受けやすい非免許無線技術の代替手段としての可能性に対し、強い関心を呼び起こしている。
中国は、工場、倉庫、鉱山、発電所、変電所、石油・ガス施設、港湾などの産業現場における5G接続の導入を加速させることを目的とした、国家主導の施策に支えられ、依然として最も成熟した国内市場である。 中国における民間の5Gネットワークの多くは通常、数十のRAN(無線アクセスネットワーク)ノードで構成されていますが、最大規模のネットワークでは、特定の遅延、信頼性、セキュリティ要件に応じて、オンプレミスまたはエッジクラウドベースのコアネットワーク機能によってサポートされる最大2,500台の専用無線機器に達することもあります。 同国における大規模なプライベート5Gネットワークの導入実績は、ビデオ監視やIoTセンサーのユースケース向けのコスト効率に優れたRedCap(Reduced Capability)デバイスを含む、特殊な非携帯電話端末に対する国内需要を牽引する重要な要因となっている。 新たな展開における主な焦点は、複数の自動化プロセスのリアルタイム調整のためのDetNet(Deterministic Networking)の機能強化や、ISAC (Integrated Sensing & Communications)など、6G時代の技術の標準化前の実装が挙げられる。この機能は、米軍にとっても優先事項となっている。中国の携帯電話事業者やベンダーも、タイ、インドネシア、モロッコ、南アフリカから、はるか遠くのペルーに至るまで、海外の製造業、鉱業、港湾などの分野におけるプライベート5Gのビジネスチャンスを追求し、国内市場を超えて事業を拡大している。
中国の国家主導型のアプローチとは対照的に、米国、カナダ、ドイツ、 英国、フランス、スペイン、イタリア、日本、韓国、台湾、オーストラリア、ニュージーランド、ブラジル、およびその他の国々における民間5Gの導入は、産業用インテリジェンス、自動化、フィジカルAI、ミッションクリティカルな通信イニシアチブの一環として、主に企業主導の投資によって推進されています。 世界的に、プライベート5Gネットワークは、生産ラインの迅速な再構成のための無線接続された機械、分散型PLC(プログラマブル・ロジック・コントローラ)環境、イントラロジスティクス向けのAGV (自動搬送車)やAMR(自律移動ロボット)によるイントラロジスティクス、複雑な産業タスクを担う準ヒューマノイド型および四足歩行ロボット、モバイルかつペーパーレスなワークフローを利用するコネクテッドワーカー、 AR(拡張現実)を活用したガイダンスやトラブルシューティング、マシンビジョンに基づく品質管理、完成車のワイヤレスソフトウェアフラッシュ、遠隔操作クレーン、無人鉱山設備、複雑な産業システムのデジタルツインモデル、NICU(新生児集中治療室)に入院中の乳児を保護者が確認するためのバーチャル訪問、 従来のソリューションではアクセスが困難な場所でのライブ放送制作、大規模スポーツイベント中の運用上重要な通信、精密農業および畜産、ドローンと運用システム間の通信、ATO(自動列車運転)、踏切や駅ホームの安全のための映像分析、航空機エンジン部品のリモート目視検査、フライトライン整備のためのリアルタイムコラボレーション、 VR(仮想現実)を活用した訓練、軍事基地やミサイル基地における自律・遠隔運用、および通信などが挙げられます。
UE(ユーザー機器)に関連する課題やエンドユーザーの消極的な姿勢、その他の初期段階の課題が徐々に解消されるにつれ、アーリーアダプターたちは、専門のインテグレーターとの協業によるネットワーク構築、従来のモバイル通信事業者を通じた投資、あるいは5G機器サプライヤーからの直接調達といった形で、プライベート5Gの長期的な可能性への信頼を確固たるものとしています。 これは、多くの国内市場で共有周波数帯や免許周波数帯の選択肢が利用可能になったことによって実現したものです。SNS Telecom & IT が過去 2 年間にわたり強調してきたように、ますます多くのプライベート 5G 導入事例が、実用的かつ具体的なメリット――特に効率性の向上、コスト削減、安全性の向上――がますます明らかになりつつある段階へと進展しています。 注目すべき事例(今年新たに追加されたものを含む)には、以下が挙げられますが、これらに限定されるものではありません:
前述のネットワークの多くは、既存の大手企業であるエリクソン、ノキア、ファーウェイ、ZTEから、サムスンやNECといった企業に至るまで、従来の無線インフラ事業者から供給された5G機器を用いて構築されていますが、RAN、モバイルコア、および伝送ネットワーク機器の代替サプライヤーは、プライベート5G市場において引き続き存在感を高めています。 特に注目すべきは、小規模なベンダーが最近、複数の地域にまたがる数十の施設に及ぶマルチサイトのプライベート5G契約を獲得し始め、つい最近まで無線インフラ大手が独占していた領域に食い込んでいるという事実である。 注目すべき事例としては、セロナ(Celona)、グローバルスター(Globalstar)のXCOM RAN事業部門、エアスパン・ネットワークス(Airspan Networks)、デル・テクノロジーズ(Dell Technologies)、ファイアセル/アクセララン(Firecell/Accelleran)、GXC(Motive Companies)、モソ・ネットワークス/サーコム(Moso Networks/Sercomm)、 Ataya、Mavenir、Baicells、Telrad Networks、BLiNQ Networks、Ceragon Networks、JMA Wireless、Microamp Solutions、Visban、Abside Networks、SEMPRE、Eridan Communications、AmpliTech、Battelle、ODC(Open RAN Development Company)、 Skylark Wireless、ANDREW(Amphenol)、Alpha Wireless、Ubiik、Ciena、Canoga Perkins、Fibrolan、Aviat、Star Solutions/BTI Wireless、EdgeNectar、Expeto、Druid Software、HPE(Hewlett Packard Enterprise)、 Cisco Systems、RADTONICS、Pente Networks、Blue Arcus、Axyom.Core、A5G Networks、Bloxtel、Oracle、Enea、Parallel Wireless、Radisys、Wilson Connectivity、Nextivity、LG Electronics、Samji Electronics、SOLiD、 EUCAST、EasyCell、HFR Mobile、Qucell(Accuver)、WNC(Wistron NeWeb Corporation)、Askey Computer、Saviah Technologies、QCT(Quanta Cloud Technology)、G REIGNS、Pegatron、Alpha Networks、CloudRAN.AI、IPLOOK、 サンウェーブ・コミュニケーションズ、コンバ・テレコム、アジアインフォ・テクノロジーズ、AI-LINK、ライトオン、 SynaXG、VHT(Viettel High Tech)、FLARE SYSTEMS、Hytec Inter、ISL Networks、Rakuten Symphony、ELUON、NextEPC(COONTEC)、Siemens、Obvios、Katela Networks、Eviden、 コントロン、テルトロニック、YateBTS、BubbleRAN、アマリソフト、キャンパス・ジーニアス、リーデル・コミュニケーションズ、ガードスタック/ブラックネッド、クムコア、アペイロオン、センドバッファー、アティカ・テクノロジーズ、IS-ワイヤレス、エフネット、ノード-H、SRS(ソフトウェア・ラジオ・システムズ)、 ベネテル、アットコア、セルキシカ、JETコネクティビティ、ニュートラル・ワイヤレス、ワイヤレス・エクセレンス、アンテビア・ネットワークス、ASOCS、ASELSAN、i2iシステムズ、PROTEI、イスクラ・テクノロジーズ、トロピコ、ニラル・ネットワークス、タイダル・ウェーブ、レカ・ワイヤレス。
ネットワークインフラへの投資には多額の初期資本が必要であり、更新が必要となるまで長年にわたり運用され続けることが想定されています。 例えば、オーストラリアの鉱業分野における多くのプライベートLTE導入事例は、運用開始から10年近くが経過した今になってようやくスタンドアロン型5Gネットワークへと置き換えられつつありますが、この移行は、適切な中波帯周波数帯域におけるAWL(エリアワイドライセンス)の導入によって可能となりました。 対照的に、UE(ユーザー端末)やデバイスの調達については、ネットワークのライフサイクルを通じて、新しいユースケース向けのエンドポイントが段階的に追加されるという、より緩やかな軌跡をたどります。 プライベートセルラーデバイスのエコシステムは、インフラ分野と一つの共通点を持っています。それは、Apple、Samsung、Zebra Technologies、Bittium、HMD、CROSSCALL、Ascom、Cybertel、TELOX、 ハイテラ、ソニム(NEXA)、シヤタ、ピュリズム、サイラス・テクノロジー、ラグギア、i.safe MOBILE、 ゲタック、パナソニック・コネクトといったスマートフォン、タブレット、ノートPC、専用端末のベンダーから、Semtech、Telit Cinterion、Quectel、Sunsea、Fibocom、Lierda、Cavli Wireless、Cradlepoint(エリクソン)、Digi International、Teltonika Networks、Inseego、BEC Technologies、 マルチテック、ペプランク、HMSネットワークス、アビアット、モクサ、ベルデン、インハンド・ネットワークス、ラントロニクス、RAD、ユーロテック、ウェスターモ、アドバンテック、AMITワイヤレス、ADLINKテクノロジー、サーコム、ロブステル、フォーフェイス、ホンディエン、PUSR、 マイクロハード、ホライゾン、デジェロ、グローバル・テレコム、エアゲイン、セレウェイ、INSYS icom、コントロン、ファンクワーク、シーメンス、アイコメラ、GE ヴェルノバ、イートロン、フェニックス・コンタクト、マイルサイト、ラジャント、ソニー、ハイビジョン、ライブユー、テラデック、TVU ネットワークス。 プライベート5Gネットワーク向けに最適化された新しいデバイスや機能強化が、引き続き市場に投入されている。最近の例をいくつか挙げると、ノキアはHMDと提携し、防衛および公共安全のユーザー向けの戦術用スマートフォンを開発した。 シーメンスは5Gルーターにエッジランタイム機能を追加し、日本の住友電気工業は、独自のAI画像圧縮アルゴリズムを統合したローカル5Gネットワーク向けミリ波端末を発売しました。これにより、高解像度のカメラ映像をデータ量を80%削減して送信することが可能になります。
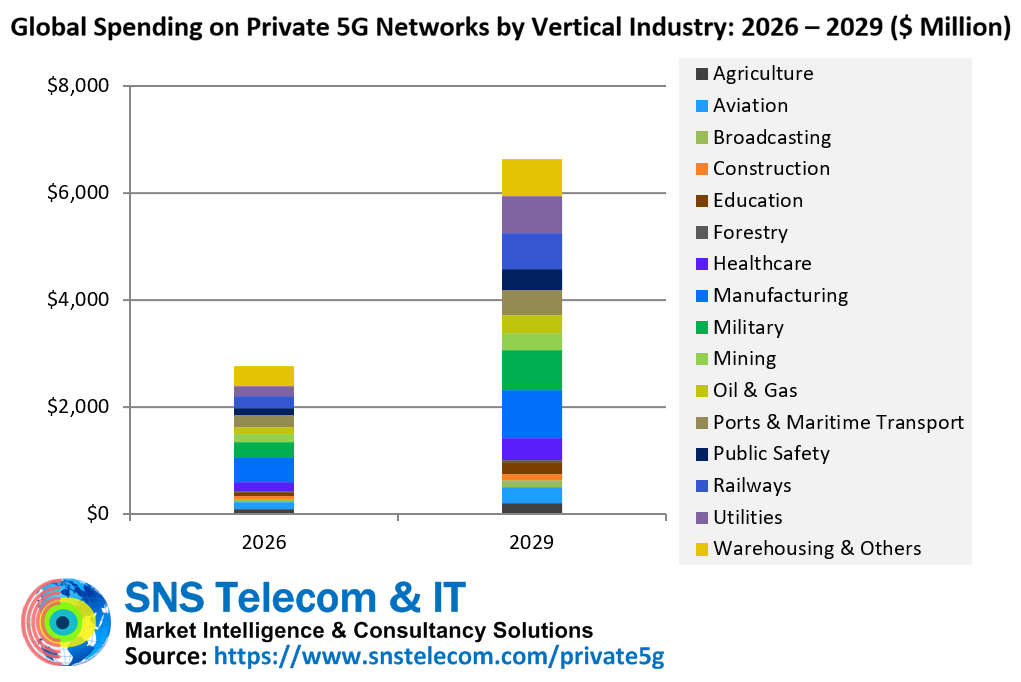
SNS Telecom & ITの予測によると、垂直産業向けプライベート5Gネットワークへの年間投資額は、2026年から2029年にかけて年平均成長率(CAGR)約34%で拡大し、2029年末までに66億ドルを超える見込みです。 この成長の大部分は、企業キャンパスや産業施設における従業員の接続性、自動化、AIアプリケーションのための、高度にローカライズされた5Gネットワークによって牽引される見込みだ。特に物理AIの導入が顕著であり、多くの産業大手企業が、プライベート5Gに接続されたAGV、AMR、ドローン、クレーン、フォークリフト、 鉱山用車両、四足歩行ロボット、さらには準ヒューマノイド型システムに依存しており、これらは原材料や部品から完成車、重厚鋼板に至るまでの荷物の自律搬送、鉱山作業における遠隔操作によるブルドーザー作業、高層倉庫での在庫棚卸し、予知保全のための目視検査、無人警備パトロール、両腕を用いた物体の操作といったタスクに活用されている。 なお、ボストン・ダイナミクスやAgiBotといったロボットメーカーは、産業環境における自社製品の接続手段として、プライベート5Gネットワークを推奨している点は注目に値する。
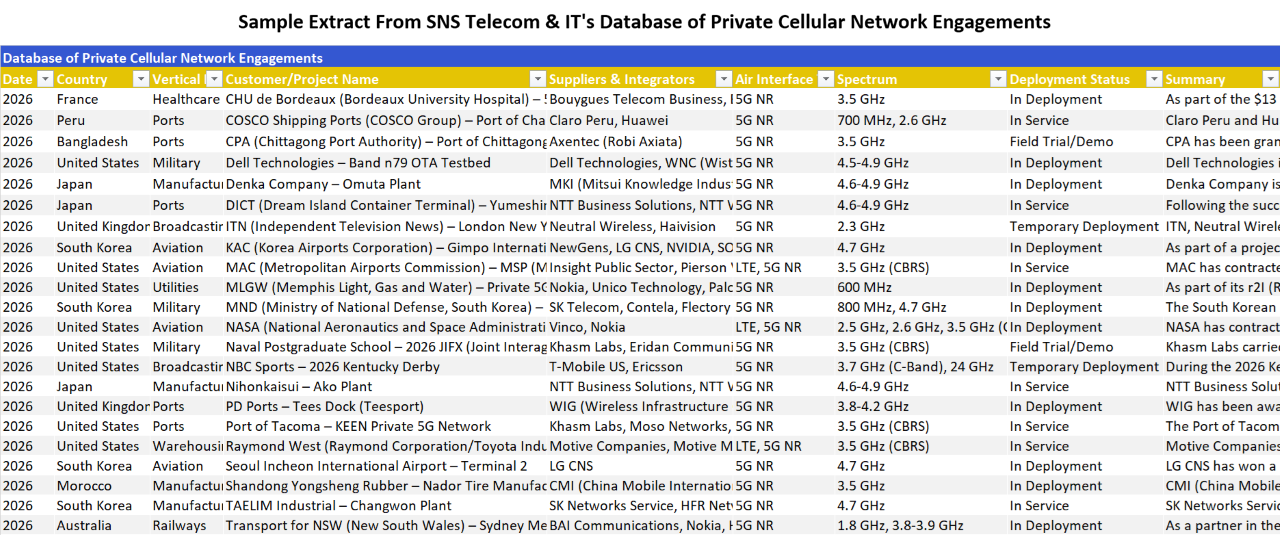
本レポートには、すべての定量予測および過去データを網羅したExcelデータシート一式に加え、2026年第2四半期時点における9,300件を超える世界中のプライベートセルラー導入事例(4,600件以上のプライベート5G導入を含む)に関する包括的なデータベースが付属しています。 また、サブ1GHz帯、ミッドバンド、ミリ波帯における400以上の周波数アクセス経路を網羅した周波数追跡データベースも含まれており、国ごとに、ローカルおよび広域のプライベートネットワーク向けの関連周波数および帯域幅の利用可能性が記載されています。

SummaryPrivate cellular networks largely remained a fringe solution in the 2G and 3G eras, although GSM-R networks for railway communications are still operational ahead of a planned transition to 5G-based FRMCS (Future Railway Mobile Communication System). The early 2010s saw the first installations of private LTE networks – including Rio Tinto's private LTE network for its Western Australia mining operations, Tampnet's offshore 4G infrastructure and iNET's 700 MHz network in the Permian Basin – marking the beginning of what has since grown into a well-established but niche segment of the wider wireless infrastructure sector. However, private 5G networks or NPNs (Non-Public Networks) based on 3GPP-defined 5G specifications are increasingly replacing LTE across many verticals, with a market potential far exceeding that of previous technology generations. There continues to be a steady rise in production-grade deployments by household names and industrial giants such as ADNOC, Airbus, ArcelorMittal, BASF, Bayer, Belden, BHP, BMW, Boliden, BP, Cargill, Celanese, Chevron, CIMPOR, COSCO Shipping, CPF (Charoen Pokphand Foods), Denka, Dot Foods, DP World, Duracell, Equinor, EMSTEEL, Etihad, Flex, Ford, Foxconn, Gerdau, Google, Hancock Prospecting, Hitachi Rail, Home Depot, Hutchison Ports, Hyundai, Intel, Inventec, Jaguar Land Rover, John Deere, LG Electronics, LS Electric, Lufthansa, LyondellBasell, Meijer, Moeve (Cepsa), Nestlé, Newmont, Nucor, OKI Electric, Outokumpu, Pegatron, PETRONAS, POSCO, Repsol, Ricoh, Robert Bosch, Salzgitter, Snam, Subaru, Takeda, Tesla, Toyota, Trinity Industries, Usiminas, Volkswagen, Walmart, WEG, Whirlpool, Xerox, Xiaomi Auto and ZF. Compared to LTE technology, private 5G networks – also referred to as 5G MPNs (Mobile Private Networks), 5G campus networks, P5G, local 5G or e-Um 5G systems, depending on geography – can address far more demanding performance requirements in terms of throughput, latency, reliability, availability and connection density. In particular, 5G's URLLC (Ultra-Reliable, Low-Latency Communications) and mMTC (Massive Machine-Type Communications) capabilities, along with a future-proof transition path to 6G networks in the 2030s, have positioned it as a viable alternative to physically wired connections for industrial-grade communications between machines, robots and control systems. Furthermore, despite its relatively higher cost of ownership, 5G's wider coverage radius per radio node, scalability, determinism, security features and mobility support have stirred strong interest in its potential as a replacement for interference-prone unlicensed wireless technologies in IIoT (Industrial IoT) environments, where the number of connected sensors and other endpoints is expected to increase significantly over the coming years. China remains the most mature national market supported by state-funded directives aimed at accelerating the adoption of 5G connectivity in industrial settings such as factories, warehouses, mines, power plants, substations, oil and gas facilities and ports. Although most private 5G networks in China typically comprise dozens of RAN (Radio Access Network) nodes, the largest networks can reach up to 2,500 dedicated radios supported by on-premises or edge cloud-based core network functions depending on specific latency, reliability and security requirements. The country's large installed base of private 5G networks is a significant factor in driving domestic demand for specialized non-handset terminals, including cost-efficient RedCap (Reduced Capability) devices for video surveillance and IoT sensor use cases. A key focus of new deployments is on 5G-Advanced features such as DetNet (Deterministic Networking) enhancements for real-time coordination of multiple automated processes and pre-standards implementations of 6G era technologies, including ISAC (Integrated Sensing & Communications) – a capability that is also a priority for the U.S. military. Chinese mobile operators and vendors have also expanded beyond their domestic market in pursuit of private 5G business opportunities in manufacturing, mining, ports and other sectors abroad, from Thailand, Indonesia, Morocco and South Africa to as far afield as Peru. In contrast to China's state-directed approach, private 5G adoption in the United States, Canada, Germany, United Kingdom, France, Spain, Italy, Japan, South Korea, Taiwan, Australia, New Zealand, Brazil and other countries is largely driven by enterprise-led investment as part of industrial intelligence, automation, physical AI and mission-critical communications initiatives. Globally, private 5G networks are progressively being implemented to support use cases as diverse as wirelessly connected machinery for the rapid reconfiguration of production lines, distributed PLC (Programmable Logic Controller) environments, AGVs (Automated Guided Vehicles) and AMRs (Autonomous Mobile Robots) for intralogistics, semi-humanoid and quadruped robots for complex industrial tasks, connected workers with mobile and paperless workflows, AR (Augmented Reality)-assisted guidance and troubleshooting, machine vision-based quality control, wireless software flashing of manufactured vehicles, remote-controlled cranes, unmanned mining equipment, digital twin models of complex industrial systems, virtual visits for parents to see their infants in NICUs (Neonatal Intensive Care Units), live broadcast production in locations not easily accessible by traditional solutions, operations-critical communications during major sporting events, precision agriculture and livestock farming, communications between drones and operational systems, ATO (Automatic Train Operation), video analytics for railway crossing and station platform safety, remote visual inspections of aircraft engine parts, real-time collaboration for flight line maintenance, VR (Virtual Reality)-based training, autonomous and remote operations at military bases and missile field communications.
With UE (User Equipment)-related challenges, end user conservatism and other teething problems continuing to wane, early adopters are affirming their faith in the long-term potential of private 5G by investing in networks built in collaboration with specialist integrators, through traditional mobile operators or independently via direct procurement from 5G equipment suppliers – made possible by the availability of shared and licensed spectrum options in many national markets. As SNS Telecom & IT has highlighted over the last two years, a growing number of private 5G installations have progressed to a stage where practical and tangible benefits – particularly efficiency gains, cost savings and safety – are becoming increasingly evident. Notable examples, featuring new additions this year, include but are not limited to:
Although many networks referenced above have been built using 5G equipment supplied by traditional wireless infrastructure players – from incumbents Ericsson, Nokia, Huawei and ZTE to the likes of Samsung and NEC – alternative suppliers of RAN, mobile core and transport network equipment are continuing to gain traction in the private 5G market. Of particular note is the fact that smaller vendors have recently begun securing multi-site private 5G contracts spanning dozens of facilities across multiple geographies, encroaching on territory that until recently had been the preserve of wireless infrastructure giants. Noteworthy examples include Celona, Globalstar's XCOM RAN business unit, Airspan Networks, Dell Technologies, Firecell/Accelleran, GXC (Motive Companies), Moso Networks/Sercomm, Ataya, Mavenir, Baicells, Telrad Networks, BLiNQ Networks, Ceragon Networks, JMA Wireless, Microamp Solutions, Visban, Abside Networks, SEMPRE, Eridan Communications, AmpliTech, Battelle, ODC (Open RAN Development Company), Skylark Wireless, ANDREW (Amphenol), Alpha Wireless, Ubiik, Ciena, Canoga Perkins, Fibrolan, Aviat, Star Solutions/BTI Wireless, EdgeNectar, Expeto, Druid Software, HPE (Hewlett Packard Enterprise), Cisco Systems, RADTONICS, Pente Networks, Blue Arcus, Axyom.Core, A5G Networks, Bloxtel, Oracle, Enea, Parallel Wireless, Radisys, Wilson Connectivity, Nextivity, LG Electronics, Samji Electronics, SOLiD, EUCAST, EasyCell, HFR Mobile, Qucell (Accuver), WNC (Wistron NeWeb Corporation), Askey Computer, Saviah Technologies, QCT (Quanta Cloud Technology), G REIGNS, Pegatron, Alpha Networks, CloudRAN.AI, IPLOOK, Sunwave Communications, Comba Telecom, AsiaInfo Technologies, AI-LINK, LITEON, SynaXG, VHT (Viettel High Tech), FLARE SYSTEMS, Hytec Inter, ISL Networks, Rakuten Symphony, ELUON, NextEPC (COONTEC), Siemens, Obvios, Katela Networks, Eviden, Kontron, Teltronic, YateBTS, BubbleRAN, Amarisoft, CampusGenius, Riedel Communications, GuardStack/Blackned, Cumucore, Apeiroon, SendBuffer, Atika Technologies, IS-Wireless, Effnet, Node-H, SRS (Software Radio Systems), Benetel, AttoCore, cellXica, JET Connectivity, Neutral Wireless, Wireless Excellence, Antevia Networks, ASOCS, ASELSAN, i2i Systems, PROTEI, Iskra Technologies, Trópico, Niral Networks, Tidal Wave and Lekha Wireless. Network infrastructure investment requires significant upfront capital and is expected to remain in service for many years before a refresh is warranted — for instance, many of Australia's private LTE deployments in the mining sector are only now being replaced by standalone 5G networks after nearly a decade in operation, a transition made possible by the introduction of AWLs (Area-Wide Licences) in suitable mid-band spectrum. By contrast, UE or device procurement follows a more gradual trajectory, with endpoints for new use cases added incrementally over the network's lifecycle. The private cellular device ecosystem shares one trait with the infrastructure segment — it is equally diverse with many OEMs and suppliers, from smartphone, tablet, laptop and specialized handset vendors such as Apple, Samsung, Zebra Technologies, Bittium, HMD, CROSSCALL, Ascom, Cybertel, TELOX, Hytera, Sonim (NEXA), Siyata, Purism, Cyrus Technology, RugGear, i.safe MOBILE, Getac and Panasonic Connect to suppliers of IoT modules, routers and other form factors such as Semtech, Telit Cinterion, Quectel, Sunsea, Fibocom, Lierda, Cavli Wireless, Cradlepoint (Ericsson), Digi International, Teltonika Networks, Inseego, BEC Technologies, MultiTech, Peplink, HMS Networks, Aviat, Moxa, Belden, InHand Networks, Lantronix, RAD, Eurotech, Westermo, Advantech, AMIT Wireless, ADLINK Technology, Sercomm, Robustel, Four-Faith, Hongdian, PUSR, Microhard, Horizon, Dejero, Global Telecom, Airgain, Celerway, INSYS icom, Kontron, Funkwerk, Siemens, Icomera, GE Vernova, Itron, Phoenix Contact, Milesight, Rajant, Sony, Haivision, LiveU, Teradek and TVU Networks. New devices and feature enhancements tailored for private 5G networks continue to enter the market. To cite a few recent examples, Nokia has partnered with HMD to develop a tactical smartphone for defense and public safety users, Siemens has enhanced its 5G routers with edge runtime capabilities, and Japan's Sumitomo Electric has launched an mmWave terminal for local 5G networks that integrates proprietary AI image compression algorithms, enabling high-definition camera footage to be transmitted with an 80% reduction in data volume.
SNS Telecom & IT projects that annual investments in private 5G networks for vertical industries will grow at a CAGR of approximately 34% between 2026 and 2029, eventually surpassing $6.6 billion by the end of 2029. A substantial proportion of this growth will be led by highly localized 5G networks for workforce connectivity, automation and AI applications in enterprise campuses and industrial facilities. The adoption of physical AI is particularly pronounced, with many industrial giants relying on private 5G-connected AGVs, AMRs, drones, cranes, forklifts, mining vehicles, quadruped robots and even semi-humanoid systems for tasks such as the autonomous transportation of loads ranging from raw materials and parts to assembled vehicles and heavy steel slabs, remote-controlled dozing in mining operations, high-bay inventory counting, visual inspections for predictive maintenance, unmanned security patrols and dual-arm object manipulation. It is worth noting that robot manufacturers such as Boston Dynamics and AgiBot recommend private 5G networks as the preferred connectivity medium for their products in industrial settings.
The report is accompanied by an Excel datasheet suite covering all quantitative forecasts and historical data, as well as an extensive database of over 9,300 global private cellular engagements – including more than 4,600 private 5G installations – as of Q2 2026. Also included is a spectrum tracking database covering over 400 spectrum access routes in the sub-1 GHz, mid-band and mmWave ranges, with associated frequencies and bandwidth availability for both local and wide area private networks on a per-country basis.
ご注文は、お電話またはWEBから承ります。お見積もりの作成もお気軽にご相談ください。本レポートと同分野(ネットワーク)の最新刊レポート
SNS Telecom & IT社の 調査レポート分野 での最新刊レポート
よくあるご質問SNS Telecom & IT社はどのような調査会社ですか?SNSテレコム&IT (SNS Telecom & IT)はドバイに拠点をおき、通信技術やモバイル機器に関する継続的な非常に詳細なデータを提供しています。無線ネットワークインフラやビッグデータ、M2M... もっと見る 調査レポートの納品までの日数はどの程度ですか?在庫のあるものは速納となりますが、平均的には 3-4日と見て下さい。
注文の手続きはどのようになっていますか?1)お客様からの御問い合わせをいただきます。
お支払方法の方法はどのようになっていますか?納品と同時にデータリソース社よりお客様へ請求書(必要に応じて納品書も)を発送いたします。
データリソース社はどのような会社ですか?当社は、世界各国の主要調査会社・レポート出版社と提携し、世界各国の市場調査レポートや技術動向レポートなどを日本国内の企業・公官庁及び教育研究機関に提供しております。
|
|