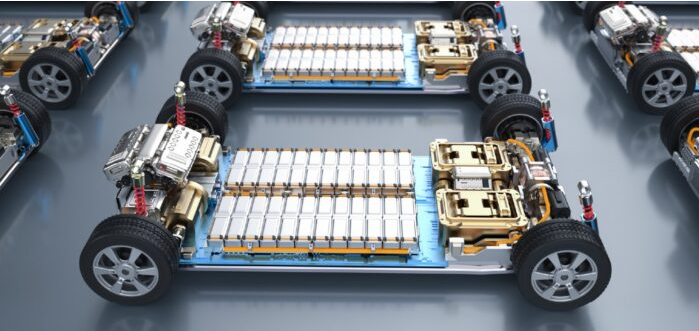
 電気自動車(EV)用バッテリーセルおよびパックの材料:世界市場 2027-2037年Electric Vehicle (EV) Battery Cell and Pack Materials: Global Market 2027-2037 電気自動車(EV)用バッテリーセルおよびパックの材料市場は、現代の駆動用バッテリーの物理的構成全体を網羅しており、セルから外側に向かって次のように分類される: 質量と価値の両面で主要な割合を占め... もっと見る

サマリー 電気自動車(EV)用バッテリーセルおよびパックの材料市場は、現代の駆動用バッテリーの物理的構成全体を網羅しており、セルから外側に向かって次のように分類される: 質量と価値の両面で主要な割合を占める正極および負極の活物質、それらの機能を可能にするセル内の不活性材料、セルのグループを接続・絶縁するモジュールレベルの材料、そしてアセンブリを収容・冷却・保護するパックレベルの構造・機能材料。 これはエネルギー転換を支える基礎的な材料市場の一つであり、急速に拡大する世界のEV産業の直下に位置し、重要鉱物、特殊化学品、先端金属、およびエンジニアリング機能性材料をほぼ同等の割合で活用している。 この市場は、単一の技術というよりは、3つの力の相互作用によって形作られています。第一にセル化学です。ニッケルやコバルトを多く含む正極からリン酸鉄系配合への移行、およびグラファイト負極へのシリコンの漸進的な導入により、どの材料が最も重要であるかが絶えず再定義されています。 2つ目はパックの構造である。従来のモジュール式パックから、セル・トゥ・パック、セル・トゥ・ボディ、セル・トゥ・シャーシといった設計への移行により、蓄えられるエネルギー単位あたりに必要な非活性構造材料の量が着実に減少している。 3つ目は供給の地理的要因です。採掘よりもはるかに重要な、精錬およびバッテリーグレードへの加工の集中度こそが、真の供給リスクがどこにあるかを決定づけています。 これらの要因が相まって、市場規模全体の拡大よりも構成の変化が速い市場が生まれています。 ほぼすべての材料で需要は拡大していますが、そのバランスは、豊富に存在し、人工的に開発された材料へと傾き、設計から排除されつつある材料からは遠ざかっています。サプライヤー、加工業者、セルおよびパックメーカー、自動車メーカー、投資家にとって、この進化し続ける部品表(材料ごとに、化学組成ごとに、アーキテクチャごとに)を理解することは、今後10年間を乗り切る上で不可欠となっています。 『電気自動車(EV)用バッテリーセルおよびパック材料:2027~2037年の世界市場』は、2027年から2037年にかけて、EV用バッテリーセルおよびパックに使用されるあらゆる材料の世界市場を定量的に分析しています。 本レポートは、最新の駆動用バッテリーの部品表全体を追跡し、各材料について、物理的な需要(年間キロトン)と市場価値(年間米ドル)の両方を年次ベースで予測しています。 その手法は厳密なボトムアップ方式を採用しています。車種セグメント別のEV販売台数をバッテリー需要(ギガワット時)に換算し、化学組成および設計ごとに定められた材料集約度係数(キロワット時あたりキログラム)を乗じた後、価格を算出します。これにより、すべての予測が車両販売台数から材料のトン数および価値に至るまで、透明性を持って追跡可能となります。 バリューチェーン全体を網羅的にカバーしています。セル側では、正極活物質(NMC、NCA、NMCA、LFP、 LMFP、LMO系)から、負極活物質(天然および合成黒鉛、シリコンおよび酸化シリコン、ならびに注視対象としてのリチウム金属)、さらにはセル内の非活物質――電解液、セパレータ、バインダー、導電性添加剤、集電体、セル筐体――まで網羅しています。 パック側では、モジュール材料(バスバー、端子、絶縁体)、パック構造材料(アルミニウム、鋼、複合材料)、およびパック機能材料(熱界面材料、冷却部品、防火材、圧縮パッド、シール材)を網羅しています。 予測は、車種別(乗用車、バン、トラック、バス、二輪車・三輪車、マイクロカー)および中国、欧州、北米、その他の地域ごとに分類されています。 数値データに加え、本レポートでは、市場を牽引する要因についても解説しています。具体的には、リン酸鉄およびシリコンへの化学組成の移行、パック設計における構造統合の革命(CTP、CTB、CTC)、持続可能性とリサイクルの課題、そして材料の入手可能性を左右するサプライチェーンの集中化や政策環境などです。 本レポートには、セルおよびパックの設計に関する詳細な分析、実使用パックの分解調査によるベンチマーク、重要材料の供給リスクに関する包括的な評価、需要および価値の統合予測、ならびに各ティアにわたる主要材料サプライヤーのプロファイルが含まれています。 本レポートは、材料メーカーや加工業者、セル・パックメーカー、自動車メーカー、投資家、政策立案者を対象としており、最も急成長している材料の流れを特定し、供給のボトルネックを予測し、バッテリー材料バリューチェーンにおける今後10年間の構造的変化に備えるために必要な、きめ細かくて内部的に整合性のある材料需要および価値データを提供します。 レポートの内容は以下の通りです:
目次 1 概要 16 1.1 レポートの範囲と主な結論 16 1.2 市場規模および主要予測(2027年~2037年) 17 1.3 需要の推進要因、機会、課題 19 1.4 地域ごとの政策動向と市場への影響 20 1.5 世界のEV販売台数およびバッテリー需要の推移 21 1.6 電池化学の展望 22 1.7 材料使用量の推移 23 1.8 セルとパックの区分 25 1.9 本レポートで取り上げる内容 25 2 はじめにおよび方法論 27 2.1 本レポートの目的と範囲 27 2.2 電気自動車の定義と駆動系仕様 27 2.3 バッテリーのバリューチェーン:セル、モジュール、パック、システム 28 2.4 本報告書で使用した材料分類法 28 2.5 予測手法およびボトムアップ需要モデル 29 2.6 主な仮定とデータソース 29 2.7 単位、表記法および通貨 31 3 EV 市場とバッテリー需要の見通し 31 3.1 交通部門の脱炭素化におけるEVの役割 32 3.2 2015年~2026年の世界のEV販売台数 32 3.3 地域別概況と政策 33 3.4 車種セグメント別のEVバッテリー需要予測 33 3.5 バッテリー生産能力と地域別シェア 34 3.6 車種セグメント別の平均バッテリー容量 36 4 リチウムイオン電池の化学的性質と技術 36 4.1 リチウムイオン電池とは? 構成要素と動作原理 36 4.2 正極の化学組成 37 4.3 負極の化学組成 38 4.4 世界の電池化学組成の構成比とその歴史的変遷 38 4.5 新たな化学組成と材料への影響 40 4.6 地域別の電池メーカーの動向 40 5 セルコストとエネルギー密度 42 5.1 セルのコスト構造と材料の役割 42 5.2 パックおよびセルの価格推移と CAM との関連性 43 5.3 正極活物質価格に対する感応度 44 5.4 化学組成別のエネルギー密度と技術のタイムライン 45 5.5 2027年~2037年のBEV用バッテリー価格予測 46 6 電池材料:正極材および重要原材料 48 6.1 正極活物質 — 概要と開発 48 6.2 負極材料の強度 48 6.3 2020年~2037年のBEV向けリチウムイオン電池の正極材料市場シェア 49 6.4 2027年~2037年の正極材需要予測 50 6.5 価格の前提条件および正極材の価値予測 52 6.6 リチウム 53 6.6.1 資源、埋蔵量、および生産地域 53 6.6.2 価格動向 54 6.6.3 需給バランスとEV需要 55 6.7 コバルト 56 6.7.1 生産地域 57 6.7.2 強度の低下とEV需要 57 6.8 ニッケル 59 6.8.1 生産地域とクラス I の制約 59 6.8.2 EV 需要 60 6.9 マンガン、鉄、リン酸塩 61 7 セル材料:負極 63 7.1 負極材料の概要 63 7.2 負極材料の需要および価格予測 63 7.3 グラファイト(天然および合成) 65 7.4 シリコンおよび酸化シリコン負極 67 7.5 リチウム金属および次世代負極 69 8 セル材料:電解質、セパレータ、バインダー、添加剤、集電体、セルケース 70 8.1 電解質 ? リチウム塩、溶媒、添加剤 70 8.2 セパレータ ? 基材フィルム(PE、PP)およびセラミックコーティング 71 8.3 バインダー ? PVDF、SBR/CMC、PAA 72 8.4 導電性添加剤 ? カーボンブラックおよびカーボンナノチューブ (CNT) 72 8.5 集電体 ? 銅箔およびアルミ箔 72 8.6 セルケースの材料 ? 円筒形、角形、パウチ型 73 8.7 セル材料の総需要および価値の予測 74 9 セルおよびセルパックの設計:CTP、CTB、CTC、および大型フォーマット 76 9.1 セル形式とトレードオフ 76 9.2 セルからモジュール、そしてパックへ? 従来のアーキテクチャ 76 9.3 セル・トゥ・パック(CTP):推進要因と課題 77 9.4 セル・トゥ・ボディおよびセル・トゥ・シャーシ(CTB/CTC):推進要因と課題 77 9.5 OEM およびセルメーカーによる構造設計に関する発表 78 9.6 材料使用量への影響および不活性材料の削減 78 9.7 パックのエネルギー密度の傾向と予測 80 9.8 保守、修理可能性、およびリサイクル可能性への影響 80 9.9 バッテリーパックの構成部品の内訳 81 10 パックおよびモジュールの材料 82 10.1 モジュールの材料:バスバー、端子、絶縁体 82 10.2 パッケージ筐体材料:構造およびカバー 83 10.3 熱界面材料(TIM) 83 10.4 熱管理:コールドプレートと冷却液ホース 85 10.5 バッテリーエンクロージャー:アルミニウム、スチール、GFRP、CFRP、ポリマー 86 10.6 パック用シーラント(FIPG、CIPG、ディスペンスフォームガスケット) 87 10.7 防火材料 88 10.8 圧縮パッドおよびフォーム 90 10.9 電気的相互接続の絶縁 90 10.9.1 相互接続におけるアルミニウムと銅の比較 91 10.9.2 バスバーの絶縁材料 91 10.9.3 車両ごとの代表的な相互接続手法 91 10.9.4 バッテリー相互接続部における材料使用量:kg/kWh の概要 91 10.9.5 電気的相互接続:アルミニウム、銅、絶縁材の予測(2027年~2037年) 92 10.10 バスバー、端子、電気相互接続 92 10.11 パック材料の総需要および価値の予測 93 11 バッテリーパックの例 95 11.1 乗用車用パックの例 95 11.2 大型車、商用車、その他の車両の例 98 11.3 セグメント横断的な設計および材料の比較 98 12 持続可能性、リサイクル性、循環性 100 12.1 材料の重要度と供給リスク 100 12.2 セルおよびパックの材料のリサイクル可能性、リサイクルを考慮した設計 100 12.3 二次供給および再生材料の入手可能性 101 12.4 ライフサイクルおよび炭素強度の考慮事項 101 12.5 規制上の推進要因 ― EU 電池規制およびリサイクル含有率に関する規則 102 13 サプライチェーンと地理的集中 103 13.1 国別の原材料供給の集中度 103 13.2 バッテリーグレードの加工材料におけるボトルネック 104 13.3 サプライチェーンの現地化と政策 104 13.4 供給リスク評価 104 14 2027年~2037年の市場予測 105 14.1 予測範囲および方法論の要約 106 14.2 主な前提条件:バッテリーサイズ、化学組成の構成、エネルギー密度 107 14.3 正極および負極材料の需要と価値 108 14.4 セル材料の総需要と価値 109 14.5 パック用材料の総需要と総額 110 14.6 素材、車種、金額別の市場総額 111 15 企業プロフィール 113 (54社の企業プロフィール) 16 参考文献 167
図表リスト 表の一覧 表1. 報告書の範囲と対象範囲 16 表2. 主な結論 16 表3. 主要市場概要(対象年度) 18 表4. グループ別素材需要(対象年度)(Mt/年) 19 表5. カテゴリー別市場規模(対象年度)(10億米ドル) 19 表6. 推進要因、制約要因、および機会 19 表7. 地域別政策の概要 20 表8. 地域別世界EV販売台数(対象年度、百万台/年) 21 表9. BEV用正極材料の市場シェア(対象年)(%) 23 表10. 特定年における負極材料構成(%) 23 表11. 化学組成別の正極金属含有量(kg/kWh) 24 表12. セルとパックの需要および価値の内訳(%) 25 表13. バリューチェーンセグメント別の対象材料 26 表14. 本報告書の目的と研究課題 27 表15. 電気自動車の種類と駆動方式の定義 27 表16. バッテリー材料の完全な分類 28 表17. 車種セグメント別の平均バッテリー容量の想定値(kWh/台) 30 表18. 化学組成別の材料構成の想定(kg/kWh) 30 表19. 主なデータソースとその役割 31 表20. 単位、表記規則および通貨 31 表21. 駆動方式別世界EV販売台数(特定年度、百万台/年) 33 表22. 地域別EV販売台数、成長率および政策動向 33 表23. 車種セグメント別EVバッテリー需要(特定年度)(GWh/年) 34 表24. 地域別のリチウムイオン電池生産能力と需要の比較(GWh/年) 35 表25. セグメント別の平均バッテリー容量およびバッテリー需要に占める割合 36 表26. 正極材料の技術ベンチマーク 37 表27. 負極材料の技術ベンチマーク 38 表28. 車種セグメントおよび走行方向別の主流化学系 39 表29. 新興化学系とその材料への影響 40 表30. 生産地域別のセルメーカーのシェア(世界のセル生産量に占める割合) 41 表31. 構成部品別のセル原価構成(セル原価に占める割合;US$/kWh) 43 表32. リチウムイオン電池の過去価格(主要年次)(US$/kWh) 44 表33. 正極材価格シナリオに基づくセルコスト(US$/kWh) 45 表34. 化学組成別のセルエネルギー密度と主要なトレードオフ 46 表35. 化学組成別のBEVパック価格予測(US$/kWh) 47 表36. 主なコスト削減要因 47 表37. セル化学組成ごとの想定材料組成(kg/kWh) 49 表38. 特定年における正極材需要予測(kt/年) 51 表39. 正極材原料価格の想定(US$/kg) 52 表40. リチウムのサプライチェーン:抽出と転換による濃縮の比較(例示、2025年) 54 表41. リチウム需要および需給バランスの予測(主要年次、kt LCE/年) 56 表42. コバルト需要の要因および予測(主要年次) 59 表43. ニッケル需要およびクラスIへのエクスポージャー(主要年次)(kt) 61 表44. 電池用派生製品の供給リスク:高純度硫酸マンガンおよび精製リン酸 62 表45. 負極材料の概要 63 表46. 負極材料の価格想定(US$/kg、電池用グレード) 65 表47. グラファイト需要予測および内訳(特定年、kt) 67 表48. シリコン負極のベンチマーク:容量、初回サイクル効率、膨張率、代表的な充填量 69 表49. 電解液の組成:塩、炭酸塩系溶媒、および添加剤 70 表50. セパレータ材料の比較(ベースフィルムおよびセラミックコーティング) 72 表51. 集電体材料の材料強度(kg/kWh) 73 表52. セル材料市場の総括(特定年度) 75 表53. メーカー別CTP/CTB/CTC設計の概要 78 表54. モジュール材料需要予測(kt/年) 82 表55. モジュール材料の価値予測(US$B) 82 表56. パックハウジング用材料需要予測(kt/年) 83 表57. パックハウジング材料の市場規模予測(US$B) 83 表58. TIMの化学組成比較(ギャップパッド、ギャップフィラー、接着剤) 84 表59. 筐体材料の比較(金属対複合材料対ポリマー) 87 表60. シーラントの硬化メカニズムと特性 88 表61. 代表的なパックごとの相互接続アプローチと材料強度(kg/kWh) 91 表62. 車両群平均の系統連系材料集約度(kg/kWh) 91 表63. インターコネクト材料の需要および価値の予測 92 表 64. パック用材料の価格想定(米ドル/kg、目安) 93 表 65. 自動車用バッテリーパックの例 96 表 66. 大型車両、商用車、その他のバッテリーシステム 98 表67. 2037年までの重要材料の需給バランス 100 表68. 材料の供給リスクマトリックス 105 表69. 車種セグメント別のバッテリー化学組成構成の想定(2037年) 107 表70. 材料組成の想定(kg/kWh、車両群平均) 108 表71. 予測の概要、2027~2037年(需要量および価値、全材料) 112 図一覧 図1. 2027年~2037年のEV用セルおよびパック材料の総需要(材料グループ別、Mt/年) 17 図2. 2027年~2037年のEVセルおよびパック用材料の市場規模(カテゴリー別)(10億米ドル) 17 図3. 地域別世界EV販売台数、2015年~2026年および2037年までの予測(百万台/年) 21 図4. 2020年~2037年のBEV用正極材料の市場シェア(%) 22 図5. 2020年~2037年の負極材料構成とシリコン採用率(%) 22 図6. 化学組成別の正極金属含有量(kg/kWh) 24 図7. 材料需要および市場価値におけるセルとパックのシェア 25 図8. バッテリーシステムの構成:セル → モジュール → パック → システム 28 図9. 需要モデルの論理:GWh × 材料集約度 → 需要と価値 29 図10. BEV/PHEV別世界EV販売台数、2015~2026年および2037年までの予測(百万台/年) 32 図11. 車種セグメント別のEVバッテリー需要、2027~2037年(GWh/年) 34 図12. 地域別のリチウムイオン電池生産能力とEV用バッテリー需要の比較、2026年/2030年/2037年(GWh/年) 35 図13. リチウムイオン電池セルの構造 37 図14. 乗用BEV向け正極材料の過去構成比、2015年~2026年(%) 39 図15. 生産地域別のセルメーカーシェア、2026年対2037年(世界セル生産量に占める割合) 41 図16. リチウムイオンセルの部品別コスト内訳(NMC811対LFP) 42 図17. 2013年~2026年のリチウムイオンパックおよびセルの出来高加重平均価格(2023年実質米ドル/kWh) 43 図18. 正極活物質価格(NMC811およびLFP)に対するセルコストの感応度 45 図19. 正極材料の種類別セルエネルギー密度(Wh/kg) 46 図20. 2027~2037年のBEVパック価格予測(US$/kWh) 47 図21. 化学組成別の正極材使用量(kg/kWh) 49 図22. BEV向けリチウムイオン電池の正極材市場シェア 50 図23. 正極材需要予測:Ni、Co、Li、Mn、Fe、P(kt) 51 図24. 主要正極材の価値予測(US$B) 52 図25. 国別のリチウム資源量および生産量 53 図26. リチウム価格の変動、2018年~2026年 54 図27. リチウムの需給動向(2027年~2037年)(kt LCE) 55 図28. EVによるリチウム需要の予測 56 図29. 国別のコバルト生産量 57 図30. リチウムイオン電池正極材におけるコバルト使用量の推移(上記画像6) 58 図31. EVによるコバルト需要の予測 58 図32. 国別ニッケル採掘量およびクラスIニッケルのシェア 60 図33. EVによるニッケル需要の予測 60 図34. EVによるマンガン、鉄、リン酸塩の需要予測 62 図35. 負極材需要予測:グラファイトおよびシリコン(kt) 64 図36. 負極材の市場規模予測(US$B) 64 図37. 地域別天然・合成黒鉛の生産量比較。 66 図38. EVによるグラファイト需要の予測 66 図39. セルエネルギー密度とシリコン含有量の関係 68 図40. シリコン負極の需要予測 68 図41. 地域別の電解液需要 71 図42. セル形式別の材料需要 73 図43. バッテリーセル用材料需要予測(kt) 74 図44. 電池セル用材料の市場規模予測(US$B) 75 図45. セル形式の市場シェア 76 図46. モジュラーパックからCTP、そしてCTB/CTCへの進化 77 図47. 重量エネルギー密度とセル・トゥ・パック比の関係 79 図48. CTP/CTCによるパック材料の削減量(kg/kWh) 80 図49. セルとパックのエネルギー密度の予測、2027~2037年 (Wh/kg) 80 図50. バッテリーパックの構成部品内訳(重量比)(上記画像6) 81 図51. パック/モジュールおよびセル形式別のTIM塗布状況 84 図52. TIM需要予測(ktpa) 85 図53. バッテリー熱管理戦略の市場シェア(空気、液体、冷媒) 86 図54. 熱管理部品の質量予測(kt) 86 図55. 筐体材料の需要予測(kt) 87 図56. パック用シーラントの需要予測(kt) 88 図57. 防火材料のカテゴリーおよび2026年の市場シェア 89 図58. 防火材料の需要予測(kt)(上記画像8) 90 図59. 圧縮パッド/発泡材の需要予測(kt)(上の画像9) 90 図60. 配線材料の材料強度 — アルミニウム、銅、絶縁体(kg/kWh) 92 図61. バッテリーパックの材料需要予測(kt) 93 図62. バッテリーパックの材料価値予測(US$B) 94 図63. セル・トゥ・モジュール(C2M)設計。 95 図64. セル・トゥ・パック(C2P)設計 96 図65. 構造的なバッテリーパック 97 図66. 例示されたバッテリーパック間の材料組成の比較(kg/kWh) 99 図67. 2027~2037年のリサイクル材料の供給見通し 101 図68. 主要材料の地理的集中度(採掘および加工) 103 図69. セルおよびパック用材料の市場総額(10億米ドル) 106 図70. 予測対象範囲マップ(材料 × 指標) 107 図71. 負極材料の需要および価値予測 108 図72. 負極材料の需要および価値の予測 109 図73. バッテリーセル用材料の需要および価値予測 110 図74. バッテリーパックの材料需要および価値の予測 111 図75. 材料別セルおよびパック材料の総需要(kt) 111 図76. 車種別セルおよびパック材料の総需要量(kt) 112

Summary
The electric vehicle (EV) battery cell and pack materials market spans the complete physical composition of a modern traction battery, organised from the cell outward: the cathode and anode active materials that dominate both mass and value, the inactive cell materials that enable them to function, the module-level materials that connect and isolate groups of cells, and the pack-level structural and functional materials that contain, cool and protect the assembly. It is one of the foundational materials markets of the energy transition, sitting directly beneath the rapidly expanding global EV industry and drawing on critical minerals, specialty chemicals, advanced metals and engineered functional materials in roughly equal measure.
The market is shaped less by any single technology than by the interaction of three forces. The first is cell chemistry: the migration away from nickel- and cobalt-rich cathodes toward iron-phosphate formulations, and the gradual infiltration of silicon into the graphite anode, continually reshape which materials matter most. The second is pack architecture: the shift from conventional modular packs toward cell-to-pack, cell-to-body and cell-to-chassis designs steadily reduces the quantity of inactive structural material required for each unit of energy stored. The third is supply geography: the concentration of refining and battery-grade processing — far more than mining — determines where genuine supply risk lies.
Together these forces produce a market whose composition shifts faster than its overall size. Demand grows across nearly every material, but the balance tilts toward abundant and engineered materials and away from those being designed out. For suppliers, processors, cell and pack manufacturers, automakers and investors, understanding this evolving bill of materials — material by material, chemistry by chemistry, and architecture by architecture — has become essential to navigating the decade ahead.
Electric Vehicle (EV) Battery Cell and Pack Materials: Global Market 2027–2037 quantifies the global market for every material that goes into an EV battery cell and pack across the 2027–2037 period. It tracks the complete bill of materials of a modern traction battery and forecasts, for each material, both physical demand (kilotonnes per year) and market value (US dollars per year) on an annual basis.
The methodology is rigorously bottom-up: EV unit sales by vehicle segment are converted into gigawatt-hours of battery demand, multiplied by chemistry- and design-specific material-intensity factors expressed in kilograms per kilowatt-hour, and then priced — so that every forecast traces transparently from vehicle volumes through to material tonnes and value. Coverage is exhaustive across the value chain. On the cell side it spans cathode active materials (nickel, cobalt, manganese, lithium, iron and phosphate across NMC, NCA, NMCA, LFP, LMFP and LMO chemistries), anode active materials (natural and synthetic graphite, silicon and silicon oxide, and lithium metal on a watching basis), and the inactive cell materials — electrolytes, separators, binders, conductive additives, current collectors and cell casing. On the pack side it covers module materials (busbars, terminals and insulation), pack structural materials (aluminium, steel and composites) and pack functional materials (thermal interface materials, cooling components, fire protection, compression pads and seals). Forecasts are segmented by vehicle type — passenger car, van, truck, bus, two- and three-wheeler and microcar — and across China, Europe, North America and the rest of the world.
Beyond the numbers, the report explains the forces driving the market: the chemistry transition toward iron-phosphate and silicon, the structural-integration revolution in pack design (CTP, CTB and CTC), the sustainability and recycling agenda, and the supply-chain concentration and policy landscape that govern material availability. It includes detailed cell and pack design analysis, real-world pack teardown benchmarks, a full critical-materials supply-risk assessment, consolidated demand and value forecasts, and profiles of the leading materials suppliers across every tier.
Designed for material producers and processors, cell and pack manufacturers, automakers, investors and policymakers, the report provides the granular, internally consistent material-demand and value data needed to identify the fastest-growing material streams, anticipate supply bottlenecks, and position for a decade of structural change in the battery materials value chain.
Report contents include:
Table of Contents
1 EXECUTIVE SUMMARY 16
1.1 Report scope and key conclusions 16
1.2 Market size and headline forecasts, 2027–2037 17
1.3 Demand drivers, opportunities and challenges 19
1.4 Regional policy landscape and its market impact 20
1.5 Global EV sales and battery demand trajectory 21
1.6 Battery chemistry outlook 22
1.7 Material intensity evolution 23
1.8 Cell versus pack split 25
1.9 Materials covered in this report 25
2 INTRODUCTION AND METHODOLOGY 27
2.1 Report objectives and scope 27
2.2 Electric vehicle definitions and drivetrain specifications 27
2.3 The battery value chain: cell, module, pack and system 28
2.4 Materials taxonomy used in this report 28
2.5 Forecasting methodology and the bottom-up demand model 29
2.6 Key assumptions and data sources 29
2.7 Units, conventions and currency 31
3 THE EV MARKET AND BATTERY DEMAND OUTLOOK 31
3.1 The role of EVs in transport decarbonisation 32
3.2 Global EV sales, 2015–2026 32
3.3 Regional snapshots and policy 33
3.4 EV battery demand forecast by vehicle segment 33
3.5 Battery manufacturing capacity and regional shares 34
3.6 Average battery capacity by vehicle segment 36
4 LI-ION BATTERY CHEMISTRY AND TECHNOLOGY 36
4.1 What is a Li-ion battery? Components and operating principle 36
4.2 Cathode chemistries 37
4.3 Anode chemistries 38
4.4 Global battery chemistry mix and its historical evolution 38
4.5 Emerging chemistries and material implications 40
4.6 Cell-manufacturer landscape by region 40
5 CELL COST AND ENERGY DENSITY 42
5.1 Cell cost structure and the role of materials 42
5.2 Historical pack and cell price and the CAM linkage 43
5.3 Sensitivity to cathode active material prices 44
5.4 Energy density by chemistry and the technology timeline 45
5.5 BEV battery price forecast, 2027–2037 46
6 CELL MATERIALS: CATHODE AND CRITICAL RAW MATERIALS 48
6.1 Cathode active materials — overview and development 48
6.2 Cathode material intensities 48
6.3 Cathode market share for Li-ion in BEVs, 2020–2037 49
6.4 Cathode material demand forecast, 2027–2037 50
6.5 Price assumptions and cathode value forecast 52
6.6 Lithium 53
6.6.1 Resources, reserves and production geography 53
6.6.2 Price behaviour 54
6.6.3 Supply–demand balance and EV demand 55
6.7 Cobalt 56
6.7.1 Production geography 57
6.7.2 Falling intensity and EV demand 57
6.8 Nickel 59
6.8.1 Production geography and Class I constraint 59
6.8.2 EV demand 60
6.9 Manganese, iron and phosphate 61
7 CELL MATERIALS: Anode 63
7.1 Anode materials — overview 63
7.2 Anode material demand and price forecast 63
7.3 Graphite (natural and synthetic) 65
7.4 Silicon and silicon-oxide anodes 67
7.5 Lithium-metal and next-generation anodes 69
8 CELL MATERIALS: Electrolyte, Separators, Binders, Additives, Current Collectors and Cell Case 70
8.1 Electrolytes — lithium salts, solvents and additives 70
8.2 Separators — base films (PE, PP) and ceramic coatings 71
8.3 Binders — PVDF, SBR/CMC, PAA 72
8.4 Conductive additives — carbon black and carbon nanotubes (CNT) 72
8.5 Current collectors — copper foil and aluminium foil 72
8.6 Cell-case materials — cylindrical, prismatic and pouch 73
8.7 Total cell material demand and value forecast 74
9 CELL AND CELL PACK DESIGN: CTP, CTB, CTC and Large Formats 76
9.1 Cell formats and trade-offs 76
9.2 From cell to module to pack — conventional architecture 76
9.3 Cell-to-pack (CTP): drivers and challenges 77
9.4 Cell-to-body and cell-to-chassis (CTB/CTC): drivers and challenges 77
9.5 OEM and cell-maker structural-design announcements 78
9.6 Impact on material intensity and inactive-material reduction 78
9.7 Pack energy-density trends and forecast 80
9.8 Servicing, repairability and recyclability implications 80
9.9 Battery pack component breakdown 81
10 PACK AND MODULE MATERIALS 82
10.1 Module materials: busbars, terminals and insulation 82
10.2 Pack housing materials: structure and cover 83
10.3 Thermal interface materials (TIMs) 83
10.4 Thermal management: cold plates and coolant hoses 85
10.5 Battery enclosures — aluminium, steel, GFRP, CFRP, polymers 86
10.6 Pack sealants (FIPG, CIPG, dispensed-foam gaskets) 87
10.7 Fire-protection materials 88
10.8 Compression pads and foams 90
10.9 Electrical interconnects insulation 90
10.9.1 Aluminium vs copper for interconnects 91
10.9.2 Busbar insulation materials 91
10.9.3 Representative interconnect approaches by vehicle 91
10.9.4 Material quantity in battery interconnects: kg/kWh summary 91
10.9.5 Electrical interconnects: aluminium, copper and insulation forecast, 2027–2037 92
10.10 Busbars, terminals and electrical interconnects 92
10.11 Total pack material demand and value forecast 93
11 BATTERY PACK EXAMPLES 95
11.1 Passenger-car pack examples 95
11.2 Heavy-duty, commercial and other vehicle examples 98
11.3 Cross-segment design and material comparison 98
12 SUSTAINABILITY, RECYCLABILITY AND CIRCULARITY 100
12.1 Material criticality and supply risk 100
12.2 Recyclability of cell and pack materials; design-for-recycling 100
12.3 Secondary supply and recycled-material availability 101
12.4 Life-cycle and carbon-intensity considerations 101
12.5 Regulatory drivers — EU Battery Regulation and recycled-content rules 102
13 SUPPLY CHAIN AND GEOGRAPHIC CONCENTRATION 103
13.1 Material supply concentration by country 103
13.2 Battery-grade processed-material bottlenecks 104
13.3 Supply-chain localisation and policy 104
13.4 Supply-risk assessment 104
14 MARKET FORECASTS 2027–2037 105
14.1 Forecast coverage and methodology recap 106
14.2 Key assumptions: battery size, chemistry mix, energy density 107
14.3 Cathode and anode material demand and value 108
14.4 Total cell material demand and value 109
14.5 Total pack material demand and value 110
14.6 Total market by material, vehicle type and value 111
15 COMPANY PROFILES 113 (54 company profiles)
16 REFERENCES 167
List of Tables/Graphs
List of Tables
Table 1. Report scope and coverage 16
Table 2. Headline conclusions 16
Table 3. Headline market summary, selected years 18
Table 4. Material demand by group, selected years (Mt/year) 19
Table 5. Market value by category, selected years (US$ billion) 19
Table 6. Drivers, restraints and opportunities 19
Table 7. Regional policy summary 20
Table 8. Global EV sales by region, selected years (million units/year) 21
Table 9. Cathode chemistry market share for BEVs, selected years (%) 23
Table 10. Anode chemistry mix, selected years (%) 23
Table 11. Cathode metal content by chemistry (kg/kWh) 24
Table 12. Cell vs pack split of demand and value (%) 25
Table 13. Materials in scope, by value-chain segment 26
Table 14. Report objectives and research questions 27
Table 15. Electric vehicle types and drivetrain definitions 27
Table 16. Full battery materials taxonomy 28
Table 17. Average battery size assumptions by vehicle segment (kWh/vehicle) 30
Table 18. Material composition assumptions by chemistry (kg/kWh) 30
Table 19. Principal data sources and their role 31
Table 20. Units, conventions and currency 31
Table 21. Global EV sales by drivetrain, selected years (million units/year) 33
Table 22. Regional EV sales, growth and policy posture 33
Table 23. EV battery demand by vehicle segment, selected years (GWh/year) 34
Table 24. Regional Li-ion manufacturing capacity vs demand (GWh/year) 35
Table 25. Average battery size and share of battery demand by segment 36
Table 26. Cathode chemistry technical benchmark 37
Table 27. Anode material technical benchmark 38
Table 28. Dominant chemistry by vehicle segment and direction of travel 39
Table 29. Emerging chemistries and their material implications 40
Table 30. Cell manufacturer share by producer region (% of global cell output) 41
Table 31. Cell cost structure by component (% of cell cost; US$/kWh) 43
Table 32. Historical Li-ion price, selected years (US$/kWh) 44
Table 33. Cell cost under cathode price scenarios (US$/kWh) 45
Table 34. Cell energy density and central trade-off by chemistry 46
Table 35. BEV pack price forecast by chemistry (US$/kWh) 47
Table 36. Principal cost-reduction levers 47
Table 37. Assumed material composition per cell chemistry (kg/kWh) 49
Table 38. Cathode material demand forecast, selected years (kt/year) 51
Table 39. Cathode raw-material price assumptions (US$/kg) 52
Table 40. Lithium supply chain: extraction vs conversion concentration (illustrative, 2025) 54
Table 41. Lithium demand and balance forecast, selected years (kt LCE/year) 56
Table 42. Cobalt demand drivers and forecast, selected years 59
Table 43. Nickel demand and Class I exposure, selected years (kt) 61
Table 44. Battery-grade derivative supply risk: high-purity manganese sulphate and purified phosphoric acid 62
Table 45. Anode materials at a glance 63
Table 46. Anode material price assumptions (US$/kg, battery-grade) 65
Table 47. Graphite demand forecast and split, selected years (kt) 67
Table 48. Silicon anode benchmark: capacity, first-cycle efficiency, expansion, typical loading 69
Table 49. Electrolyte composition: salts, carbonate solvents and additives 70
Table 50. Separator material comparison (base film and ceramic-coated) 72
Table 51. Current-collector material intensity (kg/kWh) 73
Table 52. Total cell material market summary, selected years 75
Table 53. Summary of CTP / CTB / CTC designs by manufacturer 78
Table 54. Module material demand forecast (kt/year) 82
Table 55. Module material value forecast (US$B) 82
Table 56. Pack housing material demand forecast (kt/year) 83
Table 57. Pack housing material value forecast (US$B) 83
Table 58. TIM chemistry comparison (gap pads, gap fillers, adhesives) 84
Table 59. Enclosure material comparison (metal vs composite vs polymer) 87
Table 60. Sealant cure mechanisms and properties 88
Table 61. Interconnect approach and material intensity by representative pack (kg/kWh) 91
Table 62. Fleet-average interconnect material intensity (kg/kWh) 91
Table 63. Interconnect material demand and value forecast 92
Table 64. Pack material price assumptions (US$/kg, indicative) 93
Table 65. Automotive battery pack examples 96
Table 66. Heavy-duty, commercial and other battery systems 98
Table 67. Critical material supply-demand balance to 2037 100
Table 68. Material supply-risk matrix 105
Table 69. Battery chemistry-mix assumptions by vehicle segment, 2037 107
Table 70. Material composition assumptions (kg/kWh, fleet-average) 108
Table 71. Forecast summary, 2027–2037 (demand and value, all materials) 112
List of Figures
Figure 1. Total EV cell and pack material demand by material group, 2027–2037 (Mt/year) 17
Figure 2. Total EV cell and pack material market value by category, 2027–2037 (US$ billion) 18
Figure 3. Global EV sales by region, 2015–2026 with forecast to 2037 (million units/year) 21
Figure 4. Cathode chemistry market share for BEVs, 2020–2037 (%) 22
Figure 5. Anode chemistry mix and silicon adoption, 2020–2037 (%) 22
Figure 6. Cathode metal content by chemistry (kg/kWh) 24
Figure 7. Cell vs pack share of material demand and market value 25
Figure 8. Battery system architecture: cell → module → pack → system 28
Figure 9. Demand-model logic: GWh × material intensity → demand and value 29
Figure 10. Global EV sales with BEV / PHEV split, 2015–2026 with forecast to 2037 (million units/year) 32
Figure 11. EV battery demand by vehicle segment, 2027–2037 (GWh/year) 34
Figure 12. Regional Li-ion manufacturing capacity vs EV battery demand, 2026 / 2030 / 2037 (GWh/year) 35
Figure 13. Anatomy of a Li-ion cell 37
Figure 14. Historical cathode chemistry mix for passenger BEVs, 2015–2026 (%) 39
Figure 15. Cell manufacturer share by producer region, 2026 vs 2037 (% of global cell output) 41
Figure 16. Li-ion cell cost breakdown by component (NMC811 vs LFP) 42
Figure 17. Volume-weighted average Li-ion pack and cell price, 2013–2026 (real 2023 US$/kWh) 43
Figure 18. Cell cost sensitivity to cathode active material price (NMC811 and LFP) 45
Figure 19. Cell energy density by cathode chemistry (Wh/kg) 46
Figure 20. BEV pack price forecast, 2027–2037 (US$/kWh) 47
Figure 21. Cathode material intensity by chemistry (kg/kWh) 49
Figure 22. Cathode market share for Li-ion in BEVs 50
Figure 23. Cathode material demand forecast — Ni, Co, Li, Mn, Fe, P (kt) 51
Figure 24. Critical cathode material value forecast (US$B) 52
Figure 25. Lithium resources and production by country 53
Figure 26. Lithium price volatility, 2018–2026 54
Figure 27. Lithium supply vs demand, 2027–2037 (kt LCE) 55
Figure 28. Lithium demand from EVs forecast 56
Figure 29. Cobalt production by country 57
Figure 30. Changing cobalt intensity in Li-ion cathodes (image 6 above) 58
Figure 31. Cobalt demand from EVs forecast 58
Figure 32. Nickel mining by country and Class I nickel share 60
Figure 33. Nickel demand from EVs forecast 60
Figure 34. Manganese, iron and phosphate demand from EVs forecast 62
Figure 35. Anode material demand forecast — graphite and silicon (kt) 64
Figure 36. Anode material value forecast (US$B) 64
Figure 37. Natural vs synthetic graphite production by region. 66
Figure 38. Graphite demand from EVs forecast 66
Figure 39. Cell energy density vs silicon content 68
Figure 40. Silicon anode demand forecast 68
Figure 41. Electrolyte demand by region 71
Figure 42. Material requirements by cell format 73
Figure 43. Battery cell material demand forecast (kt) 74
Figure 44. Battery cell material value forecast (US$B) 75
Figure 45. Cell format market share 76
Figure 46. Evolution from modular pack to CTP to CTB/CTC 77
Figure 47. Gravimetric energy density vs cell-to-pack ratio 79
Figure 48. Reduction of pack materials with CTP / CTC (kg/kWh) 80
Figure 49. Cell vs pack energy-density forecast, 2027–2037 (Wh/kg) 80
Figure 50. Component breakdown of a battery pack (by weight) (image 6 above) 81
Figure 51. TIM application by pack/module and cell format 84
Figure 52. TIM demand forecast (ktpa) 85
Figure 53. Battery thermal-management strategy market share (air, liquid, refrigerant) 86
Figure 54. Thermal-management component mass forecast (kt) 86
Figure 55. Enclosure material demand forecast (kt) 87
Figure 56. Pack sealant demand forecast (kt) 88
Figure 57. Fire-protection material categories and 2026 market share 89
Figure 58. Fire-protection material demand forecast (kt) (image 8 above) 90
Figure 59. Compression pad/foam demand forecast (kt) (image 9 above) 90
Figure 60. Interconnect material intensity — aluminium, copper, insulation (kg/kWh) 92
Figure 61. Battery pack material demand forecast (kt) 93
Figure 62. Battery pack material value forecast (US$B) 94
Figure 63. Cell-to-Module (C2M) design. 95
Figure 64. Cell-to-Pack design 96
Figure 65. Structural battery pack 97
Figure 66. Material composition compared across example packs (kg/kWh) 99
Figure 67. Projected recycled-material availability, 2027–2037 101
Figure 68. Geographic concentration of key materials (mining and processing) 103
Figure 69. Total cell and pack material market value (US$B) 106
Figure 70. Forecast coverage map (materials × metrics) 107
Figure 71. Cathode material demand and value forecast 108
Figure 72. Anode material demand and value forecast 109
Figure 73. Battery cell material demand and value forecast 110
Figure 74. Battery pack material demand and value forecast 111
Figure 75. Total cell and pack material demand by material (kt) 111
Figure 76. Total cell and pack material demand by vehicle type (kt) 112
ご注文は、お電話またはWEBから承ります。お見積もりの作成もお気軽にご相談ください。本レポートと同分野(エコカー)の最新刊レポートFuture Markets, inc.社の 自動車分野 での最新刊レポート関連レポート(キーワード「電気自動車(EV)」)
よくあるご質問Future Markets, inc.社はどのような調査会社ですか?Future Markets, inc.は先端技術に焦点をあてたスウェーデンの調査会社です。 2009年設立のFMi社は先端素材、バイオ由来の素材、ナノマテリアルの市場をトラッキングし、企業や学... もっと見る 調査レポートの納品までの日数はどの程度ですか?在庫のあるものは速納となりますが、平均的には 3-4日と見て下さい。
注文の手続きはどのようになっていますか?1)お客様からの御問い合わせをいただきます。
お支払方法の方法はどのようになっていますか?納品と同時にデータリソース社よりお客様へ請求書(必要に応じて納品書も)を発送いたします。
データリソース社はどのような会社ですか?当社は、世界各国の主要調査会社・レポート出版社と提携し、世界各国の市場調査レポートや技術動向レポートなどを日本国内の企業・公官庁及び教育研究機関に提供しております。
|
|